
OCBC has launched a new promotion for overseas spending, which offers cardholders 8% cashback on their foreign currency (FCY) spend for November and December 2026.
There are two catches here:
- The cashback only applies to incremental spending above your personalised spend goal, which ranges from S$1,000 to S$5,000
- There’s an overall eligibility cap of 1,000 cardmembers for Mastercard, and 2,000 cardmembers for Visa, so this is one of those “spend and pray” promotions where there’s no guarantee of receiving the reward
However, what’s great about this promotion is the relative lack of exclusions. Even donations, education, government services, hospitals and utility bills will count towards the qualifying spend and earn cashback.
This is a targeted offer, so you must have received an eDM, SMS or OCBC app notification inviting you to participate.
OCBC cards offering 8% rebate on FCY spending
Each targeted OCBC cardholder will have received a personalised qualifying spend amount (QSA), which they must meet through spending from 1 November to 31 December 2026.
Every dollar they spend above this amount will earn 8% cashback, capped at S$168 for the entire promotional period. This means that the ceiling amount which can earn cashback is your QSA + S$2,100 (S$168 ÷ 0.08).
While it’s not stated in the T&Cs, I’ve confirmed with OCBC that there are three possible QSAs:
| QSA | Amount Eligible to Earn 8% Cashback | Total Spend |
| S$1,000 | S$2,100 | S$3,100 |
| S$3,000 | S$2,100 | S$5,100 |
| S$5,000 | S$2,100 | S$7,100 |
Spending must be made on the Visa or Mastercard whose last six digits match the six digits specified in the invitation to participate. This means you won’t be able to combine spending across different OCBC cards, though spending on supplementary cards linked to the same account will be aggregated.
OCBC has provided the following worked examples of a cardholder with a QSA of S$5,000.
|
Example 1: • Cashback is calculated as S$2,700 × 8% = S$216 As the Cashback is capped at S$168, Martin will receive S$168 Cashback, subject to the Redemption Cap. Example 2: • Cashback is calculated as S$1,900 × 8% = S$152 Martin will receive S$152 Cashback, subject to the Redemption Cap. Example 3: As such, no Cashback will be awarded. |
How is eligibility determined?
There is an overall redemption cap that applies across all QSAs.
- Visa cards: 2,000 cardmembers
- Mastercard: 1,000 cardmembers
OCBC determines eligibility based on the date on which cardholders first exceeded their QSA. Where there is a tie, the cardmember with a higher amount of spending above their QSA wins.
| The Cashback is awarded on a first-come-first-served basis, determined by the date on which an Eligible Cardmember’s Eligible Spend first exceeds the applicable Qualifying Spend Amount and is successfully posted to the Eligible Card account.
If the Redemption Cap is reached and two or more Eligible Cardmembers qualify on the same date, priority will be given to the Eligible Cardmember with the higher amount of Eligible Spend exceeding the applicable Qualifying Spend Amount. |
Therefore, if you’re planning to participate, try and hit your QSA as early as you can. After that, you can take it easy with the remaining S$2,100 of spend — the spend that actually earns 8% cashback.
While refunded transactions will of course not count towards your QSA, it’s less clear whether it costs you your place in the “queue”. Keep that in mind, if you plan to hit your QSA with an early booking you might later cancel.
Posting date, not transaction date
QSAs are tracked based on posting date, not transaction date. Therefore, transactions made towards the end of October may count, provided they post from 1 November onwards.
On the flip side, it also means that transactions made towards the end of December may not count, if they post after 31 December 2026.
What counts towards the QSA?
Eligible spend consists of online and offline transactions charged in FCY, excluding:
- Transactions converted to Singapore Dollars via Dynamic Currency Conversion (DCC)
- Payments or transactions relating to annual card fees, insurance premiums, Cash-On-Instalment, Instalment Payment Plans, PayLite, extended payment plan, income tax payment, bill payments made via Internet Banking, AXS or SAM network, interest, late payment charges, goods and services taxes, cash advances, balance transfers, bus/MRT transactions, Transit top-up and other bank fees and charges
- Transactions made at merchants classified under the following Merchant Category Codes
(“MCCs”): 4829, 6051, 6211, 6300, 6540, 9211, 9222, 9223, 9311, 9402, 9405
Interestingly, the excluded MCCs relate to quasi-cash transactions, insurance premiums, tax payments, fines and postal services. However, OCBC’s other rewards exclusions — namely charitable donations, education, government services (at least those under MCC 9399), hospitals and utilities — are not mentioned here.
I’ve checked with the OCBC team, and can confirm that this is intentional.
Any transaction that is not mentioned in the exclusions list for this particular promotion, if charged in FCY, will count towards QSA and earn the 8% cashback.
For example, if my QSA is S$1,000, and I spend S$1,500 on an overseas hospital bill (MCC 8062) with my OCBC 90°N Mastercard, I will earn S$40 of cashback (S$500 x 8%). I will not earn any 90°N Miles, however, as MCC 8062 is excluded from base rewards.
So that’s a very good use case for this promotion — if you can’t earn any rewards on these transactions with other cards, you might as well spend with your targeted OCBC card to earn some cashback.
| ❓ Can I use Amaze? |
 To pre-empt the inevitable “can I use Amaze” question, no, you can’t. Amaze converts all transactions into SGD, and this promotion only applies to spending made in FCY. |
When will the cash rebate be credited?
Eligible cardmembers will receive their cash rebate by 31 March 2027.
Terms & Conditions
The terms and conditions for this promotion can be found below:
Is it worth it?
OCBC cards have a 3.25% FCY fee, which is included in the QSA calculation. On paper, 8% cashback is more than enough to cover that, but because the cashback only applies to spend above the QSA, whether you come out ahead depends on what QSA you’ve been assigned.
S$1,000 QSA
Assuming your QSA is S$1,000, the 8% cashback breaks even with the 3.25% FCY fee at around S$1,649. Spend beyond that and you’re turning a profit, so to speak, with the maximum gain of S$70.42 at S$3,100.
| 💳 QSA of S$1,000 |
|||
| Card Spend (inclusive of FCY fee) |
FCY Fee* (3.25%) |
Cashback (8%) |
Nett |
| S$1,000 | S$31.48 | None | -S$31.48 |
| S$1,250 | S$39.35 | S$20 | -S$19.35 |
| S$1,500 | S$47.22 | S$40 | -S$7.22 |
| S$1,750 | S$55.08 | S$60 | +S$4.92 |
| S$2,000 | S$62.95 | S$80 | +S$17.05 |
| S$2,250 | S$70.82 | S$100 | +S$29.18 |
| S$2,500 | S$78.69 | S$120 | +S$41.31 |
| S$2,750 | S$86.56 | S$140 | +S$53.44 |
| S$3,000 | S$94.43 | S$160 | +S$65.57 |
| S$3,100 | S$97.58 | S$168 | +S$70.42 |
| *Note: Since card spend includes the FCY fee, the 3.25% fee works out to about 3.15% of card spend |
|||
S$3,000 QSA
Assuming your QSA is S$3,000, the 8% cashback breaks even with the 3.25% FCY fee at around S$4,946, which leaves a very narrow window to come out ahead. Even at the optimal spend of S$5,100, you only gain S$7.47 overall.
| 💳 QSA of S$3,000 |
|||
| Card Spend (inclusive of FCY fee) |
FCY Fee* (3.25%) |
Cashback (8%) |
Nett |
| S$3,000 | S$94.43 | None | -S$94.43 |
| S$3,250 | S$102.30 | S$20 | -S$82.30 |
| S$3,500 | S$110.17 | S$40 | -S$70.17 |
| S$3,750 | S$118.04 | S$60 | -S$58.04 |
| S$4,000 | S$125.91 | S$80 | -S$45.91 |
| S$4,250 | S$133.78 | S$100 | -S$33.78 |
| S$4,500 | S$141.65 | S$120 | -S$21.65 |
| S$4,750 | S$149.52 | S$140 | -S$9.52 |
| S$5,000 | S$157.38 | S$160 | +S$2.62 |
| S$5,100 | S$160.53 | S$168 | +S$7.47 |
| *Note: Since card spend includes the FCY fee, the 3.25% fee works out to about 3.15% of card spend |
|||
S$5,000 QSA
Assuming your QSA is S$5,000, it’s impossible to fully offset the 3.25% FCY fee with the 8% cashback. But remember: the idea here isn’t so much to fully offset the FCY fee, but to offset the cost on overseas spending you’d be doing anyway. If you were going to spend S$7,100 in FCY anyway, this promotion takes S$168 off the bill, while still allowing you to earn miles.
| 💳 QSA of S$5,000 |
|||
| Card Spend (inclusive of FCY fee) |
FCY Fee* (3.25%) |
Cashback (8%) |
Nett |
| S$5,000 | S$157.38 | None | -S$157.38 |
| S$5,250 | S$165.25 | S$20 | -S$145.25 |
| S$5,500 | S$173.12 | S$40 | -S$133.12 |
| S$5,750 | S$180.99 | S$60 | -S$120.99 |
| S$6,000 | S$188.86 | S$80 | -S$108.86 |
| S$6,250 | S$196.73 | S$100 | -S$96.73 |
| S$6,500 | S$204.60 | S$120 | -S$84.60 |
| S$6,750 | S$212.47 | S$140 | -S$72.47 |
| S$7,000 | S$220.34 | S$160 | -S$60.34 |
| S$7,100 | S$223.49 | S$168 | -S$55.49 |
| *Note: Since card spend includes the FCY fee, the 3.25% fee works out to about 3.15% of card spend | |||
Another way of viewing this is that you earn an effective rebate ranging from 2.4% to 5.4%, depending on your QSA, and assuming you spend the ideal amount (QSA + S$2,100).
| QSA | Ideal Spend | Effective Rebate (Before FCY Fee) |
| S$1,000 | S$3,100 | 5.4% |
| S$3,000 | S$5,100 | 3.3% |
| S$5,000 | S$7,100 | 2.4% |
This is on top of the regular miles that you’ll earn from your OCBC card.
What do OCBC cards earn on FCY spend?
Here’s a quick recap of how many miles you can expect to earn with OCBC cards, for FCY spend.
| Card | FCY Earn Rate | Remarks |
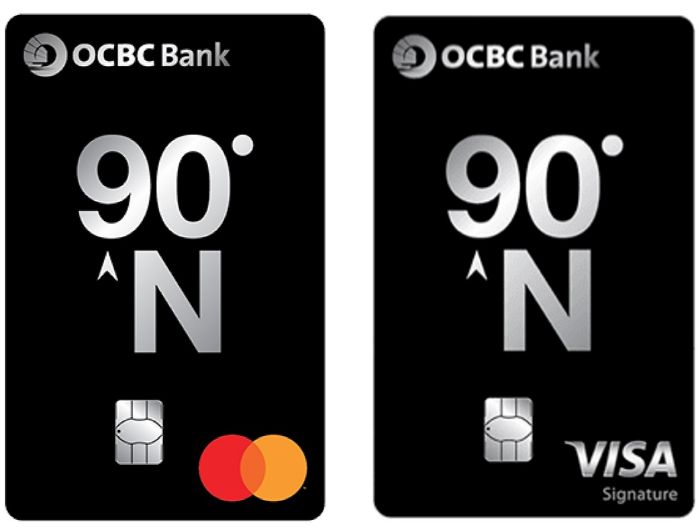 OCBC 90°N Cards |
2.1 mpd | No cap |
 OCBC VOYAGE |
2.2 mpd | No cap |
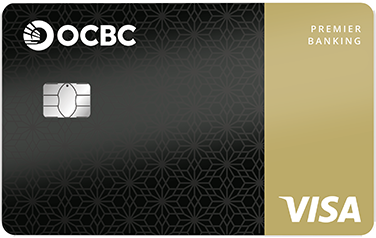 OCBC Premier Visa Infinite |
2.28 mpd | No cap |
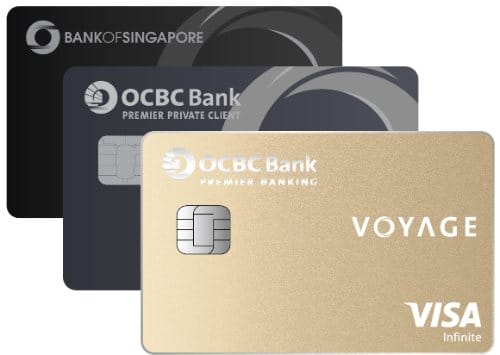 OCBC VOYAGE (Premier, PPC, BOS) |
2.3 mpd | No cap |
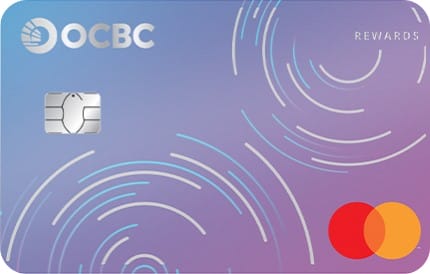 OCBC Rewards Card |
4 mpd | Eligible bonus categories only, capped at S$1.1K per c. month |
Conclusion
OCBC’s new overseas spending promotion offers 8% cashback on FCY spending above your personalised QSA, capped at S$168. How good a deal it is depends on what QSA you’ve been assigned.
I’d say a S$1,000 QSA is a no-brainer for participation, because you can stack a 5.4% rebate with the usual credit card miles, and you come out ahead even after FCY fees. It’s more marginal at S$3,000 or S$5,000, since the effective rebate shrinks, and you’ll need to spend a lot more before qualifying — which raises the risk of missing out on the redemption cap.
That aside, the promotion is particularly useful for FCY transactions that wouldn’t otherwise earn rewards with most cards, like hospital bills or education fees.
Just remember that there’s no guarantee you’ll actually get the reward, given the eligibility cap. If you want to participate, hit your QSA as soon as you can.
