
The Chocolate Visa Card is no longer the only way of earning “free” miles on overseas spending, now that the Trust Freedom Card is in the picture. That said, it remains a useful option for bill payments, education fees and charitable donations.
However, some people are understandably wary of using it, because it’s a debit card. This means that any successful transaction, legitimate or not, is immediately deducted from your balance. A random BIN attack (where fraudsters generate and test card numbers in bulk) is a mild inconvenience with a credit card, but with a debit card, you could be out of pocket until your dispute is resolved.
The traditional solution has been to keep the Chocolate Visa locked whenever it’s not in use. But Chocolate Finance has now introduced a new way of ringfencing your money: Jars.
How Chocolate Jars work
Chocolate Jars allow users to segregate their Chocolate Finance funds into separate pots, allocating them towards different goals such as an emergency fund, a holiday or a home.
Moving money into a Jar doesn’t cost you anything. Interest is still paid on your aggregated balance across your main account and all Jars, and the S$5,000 minimum ADB required to earn Max Miles is based on the aggregated balance too.
| Chocolate Finance Returns (🇸🇬 SGD Balance) |
||
| Balance | Rate (till 31 Oct 26) |
Rate (from 1 Nov 26) |
| Up to S$20,000 | 2.0% p.a. | 2.2% p.a. |
| S$20,000 to S$100,000 | 1.8% p.a. | 1.9% p.a. |
| S$100,000 to S$150,000 | Up to 1.8% p.a.* | 1.9% p.a. |
| Above S$150,000 | Up to 1.9% p.a.* | |
| *Not guaranteed under the top-up programme |
||
But Jars have an “off-label” use too — since money inside a Jar can’t be spent through the Chocolate Visa Card, you could park the bulk of your funds here, and leave a smaller balance in your main account for spending via the Chocolate Visa.
Creating a Jar is simple: tap on Jars on the home page, name the Jar, and decide how much you want to put inside.
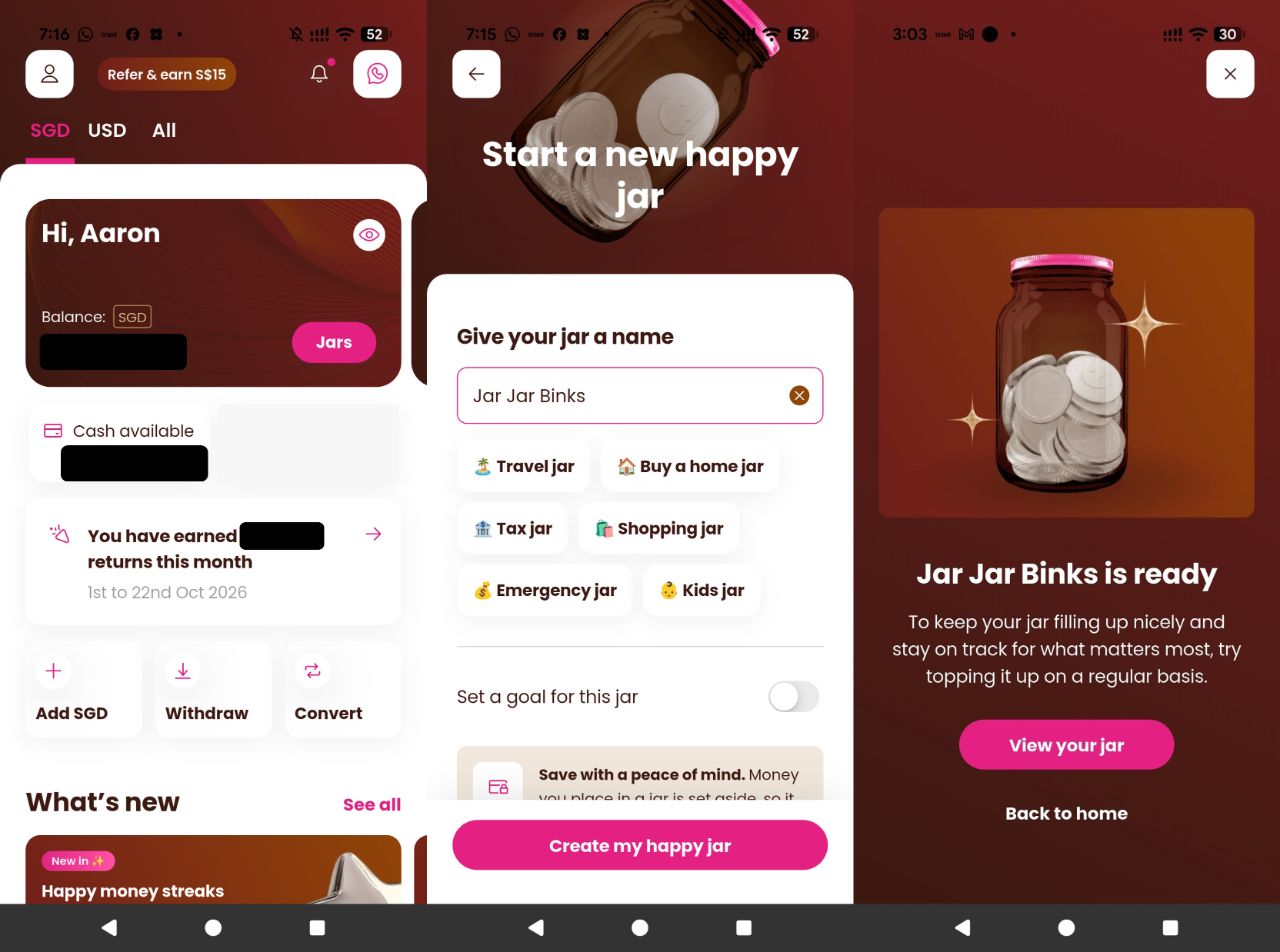
If you want to use Jars as a spending firewall of sorts, you’ll need to adopt a “top up as you go” habit. For example, if you have S$50,000 with Chocolate Finance, you might keep S$49,000 in a Jar and S$1,000 in your main account, enough to cover a month’s worth of bills.
When a larger payment comes along, you move the required amount out of the Jar just before paying. These transfers are instant, so it should only add a few seconds to the process.
The general idea is that a fraudster who successfully manages to charge your card can only drain whatever’s sitting in the main account, and not your entire balance.
Jars or locking your card?
Locking the card stops all transactions, but you’ll need to remember to re-lock it after every use. Forget just once, and your full balance is exposed. Jars cap the risk even when the card is unlocked.
There’s nothing stopping you from doing both if you’d prefer. Think of Jars as an additional layer of protection.
Reminder: Final month to enjoy upsized Miles for Returns
 |
|||
| Apply | |||
| Open a Chocolate Finance account via SingSaver and get up to S$120 cash or S$130 Grab vouchers. T&Cs apply. |
Here’s a reminder that November is the final month for Chocolate customers to enjoy an upsized Miles for Returns rate of 80 Max Miles per S$1. For example, if your returns for 1-30 November 2026 are S$100, you can convert up to S$100 into 8,000 Max Miles once 1 December 2026 comes around.
The rate will revert to the regular 62.5 Max Miles per S$1 for returns earned from 1 December 2026 onwards.
In order to participate in Miles for Returns (or earn Max Miles on the Chocolate Visa Card), you must have maintained a minimum average daily balance (ADB) of S$5,000 in your Chocolate SGD account in the previous month. Therefore, your ability to convert returns in December depends on your balance in November.
Do note that if your Chocolate Visa Card is locked, you won’t see the option to convert your returns into miles. You’ll need to unlock your card first, do the conversion, then lock it again if you wish.
Conclusion
Chocolate Finance’s new Jars feature was not primarily designed as a security feature, but you can use it like this nonetheless. By keeping most of your money in a Jar and only a small float in your main account, you cap the most you could lose to a BIN attack, without giving up any interest.
You can continue locking your card if it provides better peace of mind, but this acts as an additional line of defence.

There is already a transaction, daily, and monthly limit you can set. So why spend time moving money to/from Jars when there is already simple functionality there to protect your money already!
As if you spend the same every month 🤷🏻♂️ The effort spend adjusting your limit when there’s an unusually large spend might be even more than moving money and comes with a cooldown also.
What kind of moron that don’t want more features?
You want to know who is the moron? It is YOU. Go and educate yourself dimwit. First of all the maximum that ANYONE using the Chocolate Card can set as their transaction limit is $1000. So your monthly spend is largely irrelevant – why? Because unless you are stupid, the minute someone does a transaction fraudulently up to that $1,000 limit you are going to see it, and do something about it, surely? So seeing as you seem too stupid to understand basics, for your case, do this. Set your transaction limit at $1000, which is the maximum you are… Read more »
Lol, ok, happy going the long way then, and may you forever enjoy fraud transaction of $500 or $200 or whatever just under the limit that you set 🤪 Not sure the point of getting so angry and so invested, as if your “tHe fUnCtIoNaLiTy HaS BeEn tHeRe bEfOrE” will change anything
I will just lock $5000 of my money in a jar and sleep well at night and can immediately transfer any amount of them out if I need to make a payment