
Back in mid-June 2026, Standard Chartered cardholders received a weekend fright, when the SC mobile app started displaying a 2.5% fee for EasyBill transactions, instead of the regular 1.9%.
Fortunately, sanity was quickly restored the following week, when Standard Chartered confirmed that the increased rate was an error, and refunded the excess fees to affected customers.
But it looks like that exercise was indeed a test balloon, because the 2.5% fee has returned, and this time, it looks like they’re serious.
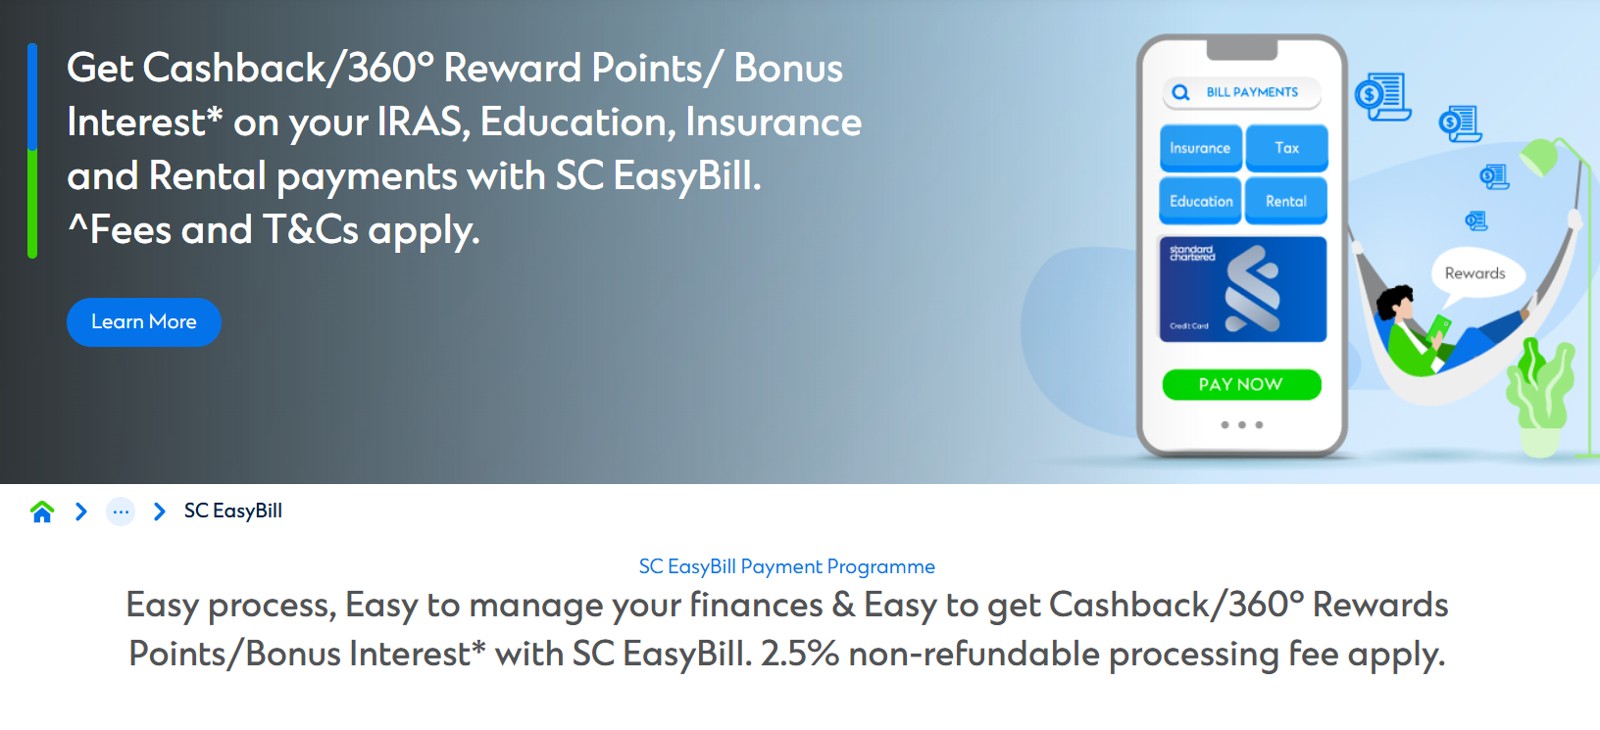
SC EasyBill increases admin fee to 2.5%
 |
| SC EasyBill |
Standard Chartered has quietly increased the EasyBill admin fee to 2.5%, effective immediately.
Why do I think it’s real this time and not just a false alarm? Well, it’s not just the app that’s been updated — the website and FAQ have been changed as well.
|
Is there a fee for SC EasyBill? Yes, there is a non-refundable, up to 2.5% processing fee applicable for each eligible SC EasyBill transaction. The SC EasyBill fee is not a fixed amount and will vary according to the SC EasyBill facility chosen on the Online Application. During the application of SC EasyBill, the fee will be reflected once the type of eligible payment (IRAS, Rental, Education or Insurance) is selected and prior to submitting the online application. |
Despite what the FAQs say about the fee not being a fixed amount, it’s the same regardless of which category of payment I choose. So I don’t know what Standard Chartered means here, unless they’re targeting customers with different offers?
| 💳 SC EasyBill Payment Categories | |
| Category | Examples |
| Tax Payments |
|
| Education |
|
| Insurance |
|
| Rent |
|
What does this mean for EasyBill?
The table below summarises how EasyBill’s cost per mile will increase, when going from a 1.9% to 2.5% fee.
| Card | Earn Rate | Cost Per Mile 1.9% fee |
Cost Per Mile 2.5% fee |
 SC Beyond Card Priority Private Priority Banking Apply |
2 mpd | 0.95¢ | 1.25¢ |
| SC Beyond Card Regular Apply |
1.5 mpd | 1.27¢ | 1.67¢ |
 SC Visa Infinite Step-Up Rate Apply |
1.4 mpd* | 1.36¢ | 1.79¢ |
 SC Journey Card Apply |
1.2 mpd | 1.58¢ | 2.08¢ |
| SC Visa Infinite Regular Rate Apply |
1 mpd | 1.9¢ | 2.5¢ |
 SC Priority Banking Visa Infinite Apply |
1 mpd | 1.9¢ | 2.5¢ |
| *1.4 mpd with min. S$2,000 overall spend in a statement month, otherwise 1 mpd |
|||
As you can see, a 2.5% fee changes everything. Cards which were a maybe under the 1.9% fee structure, like the Journey, Visa Infinite and Priority Banking Visa Infinite, all land north of 2 cents per mile with a 2.5% fee. That’s way too much to be paying for miles, given the existence of cheaper alternatives.
This nerf is going to be especially painful for SC Beyond Cardholders, who might have been enticed into getting the card by the prospect of buying miles at just 0.95 cents each — a price that’s almost impossible to lose (since you can use miles to pay for Singapore Airlines or Scoot tickets at 1 cent each). 1.25 cents is still good, but a 30% increase will be difficult to swallow.
Mind you, this isn’t the only nerf to SC EasyBill in recent times. Earlier this year, Standard Chartered capped users at one bill payment per category, per month. Talk about a rug pull!
What are the alternatives?
Not great, to be frank.
CardUp
Earlier this year, Visa and Mastercard hiked fees for payment platforms like CardUp, which caused admin fees to increase by up to 36%. To give you an idea of how bad that was, the lowest promotional fee now available with CardUp is roughly equivalent to the most expensive promotional fee at the start of the year!
But here’s what’s really interesting. The revised EasyBill cost per mile for the SC Beyond Card (1.25 cpm for PP/PB, 1.67 cpm for Regular) is just a hair’s breadth below CardUp’s cost per mile (1.26 cpm for PP/PB, 1.68 cpm for Regular), based on the year-round 2.59% promotion for Mastercards.
Coincidence? You tell me.
| Card | Earn Rate | Cost Per Mile |
| SC Beyond Card Priority Private Priority Banking Apply |
2 mpd | 1.26¢ 2.59% fee |
| SC Visa Infinite Apply |
1.4 mpd |
1.57¢ 2.25% fee 1.71¢ 2.45% fee |
| SC Beyond Card Regular Apply |
1.5 mpd | 1.68¢ 2.59% fee |
For what it’s worth, if you have a SC Visa Infinite Card, then CardUp is the cheaper option. With Visa fees ranging from 2.25-2.45%, the cost per mile will go no higher than 1.71 cents (compared to 1.79 cents with EasyBill).
Citi PayAll
Citi PayAll is similar to SC EasyBill in the sense that it’s a bank-backed payment platform. This means that payments are basically internal funds transfers, which cost less than having to pay Visa and Mastercard to facilitate.
SC EasyBill’s revised 2.5% fee is still lower than Citi PayAll’s 2.6%, which means that in most cases, it’ll be the cheaper option. However, Citi PayAll has a much broader scope of supported payments, including utility bills, renovations, charitable donations, maintenance fees, and the all-encompassing “payment for retail goods and services”.
| Card | Earn Rate | Cost Per Mile 2.6% fee |
 Citi ULTIMA |
1.6 mpd | 1.63¢ |
 Citi Prestige Apply |
1.3 mpd | 2¢ |
 Citi PremierMiles Apply |
1.2 mpd | 2.17¢ |
 Citi Rewards Apply |
0.4 mpd | 6.5¢ |
Conclusion
Standard Chartered has increased the fee for EasyBill from 1.9% to 2.5%, which effectively rules out using it outside of a promotion, unless you have an SC Beyond Card, or SC Visa Infinite with the step-up earn rate. It also ever-so-slightly undercuts CardUp’s rates, a decision which feels carefully calibrated.
To be fair, the writing was already on the wall earlier this year, when a cap was put on the number of payments that could be made each month. Clearly, SC EasyBill is seeing some enthusiastic usage, and the bank wants to dial that back.
(HT: JHH)

Just curious – why does the bank want to curb usage? Doesn’t these transactions bring them profit? Some profit is better no profit right?
they realized that their offer was way better than all their competition, and they are leaving value on the table for themselves….
Just curious – why does the bank want to curb usage? Doesn’t these transactions bring them profit? Some profit is better than no profit right?
We don’t know the usage and user patterns that SCB tracks, nor do we know exactly their cost per mile from SQ/CX. I suppose more profit is better than a little profit? Or could it be the users are heavily skewed to Beyond PB? I know I got the the card mostly for the 0.95 cpm and while I wouldn’t say I was overusing it, the monthly limit has sort of been disappointing for me. I haven’t paid $ for SQ tickets for a while.
The 0.95cpm tax payment facility was the only reason why we got the beyond card too.
With the annual fee of $1635 for 100K miles sign up bonus or 80K miles renewal bonus, the 1.25cpm for tax payment is no longer an attractive option even with the ability to double dip tax payments. To even hit 1.3cpm with the payable annual fee, payable tax needs to be around $168K (new sign up) or $298K (renewal) with double dipping…
May I ask how you calculate that? The tax payment facility is still 1.9%. Using your 168k tax bill as an example and taking 80k renewal miles for 1635 AF, I calculated total cost at 1.16 cpm, assuming we don’t spend a single cent on the card for anything else at all. (1635 + 0.019 x 168000)/(80000+336000). To hit 1.3 cpm is possible with a lower tax bill. And this is without double dipping. Is my calculation wrong? Let me know, always glad to learn.
Ah yes, you are right. I had mistakenly utilized in my calculation that both tax payment and easybill are changing to 2.5% transaction fee. Didn’t realize they kept the tax payment facility at 1.9%! Thought both were changed.
With 1.9% remaining for tax payment facility then the threshold for an arbitrary 1.2cpm is then 26K payable tax for double dipping and 46.5k for only using tax payment facility. Still better than cardup and citipayall then…
Not able to edit my response, so can only add that the 26K and 46.5K are wrong calculation again :X
Ah yes, you are right. I had mistakenly utilized in my calculation that both tax payment and easybill are changing to 2.5% transaction fee. Didn’t realize they kept the tax payment facility at 1.9%! Thought both were changed.
For lower tax amount it’s better not to double dip if targeting below 1.2cpm. Need about 168K payable tax if double dipping and 135K payable tax if only using tax payment facility.