
Here’s The MileLion’s review of the DBS Chromo Card, which invites cardholders to “live in full colour” — all five of them, I guess.
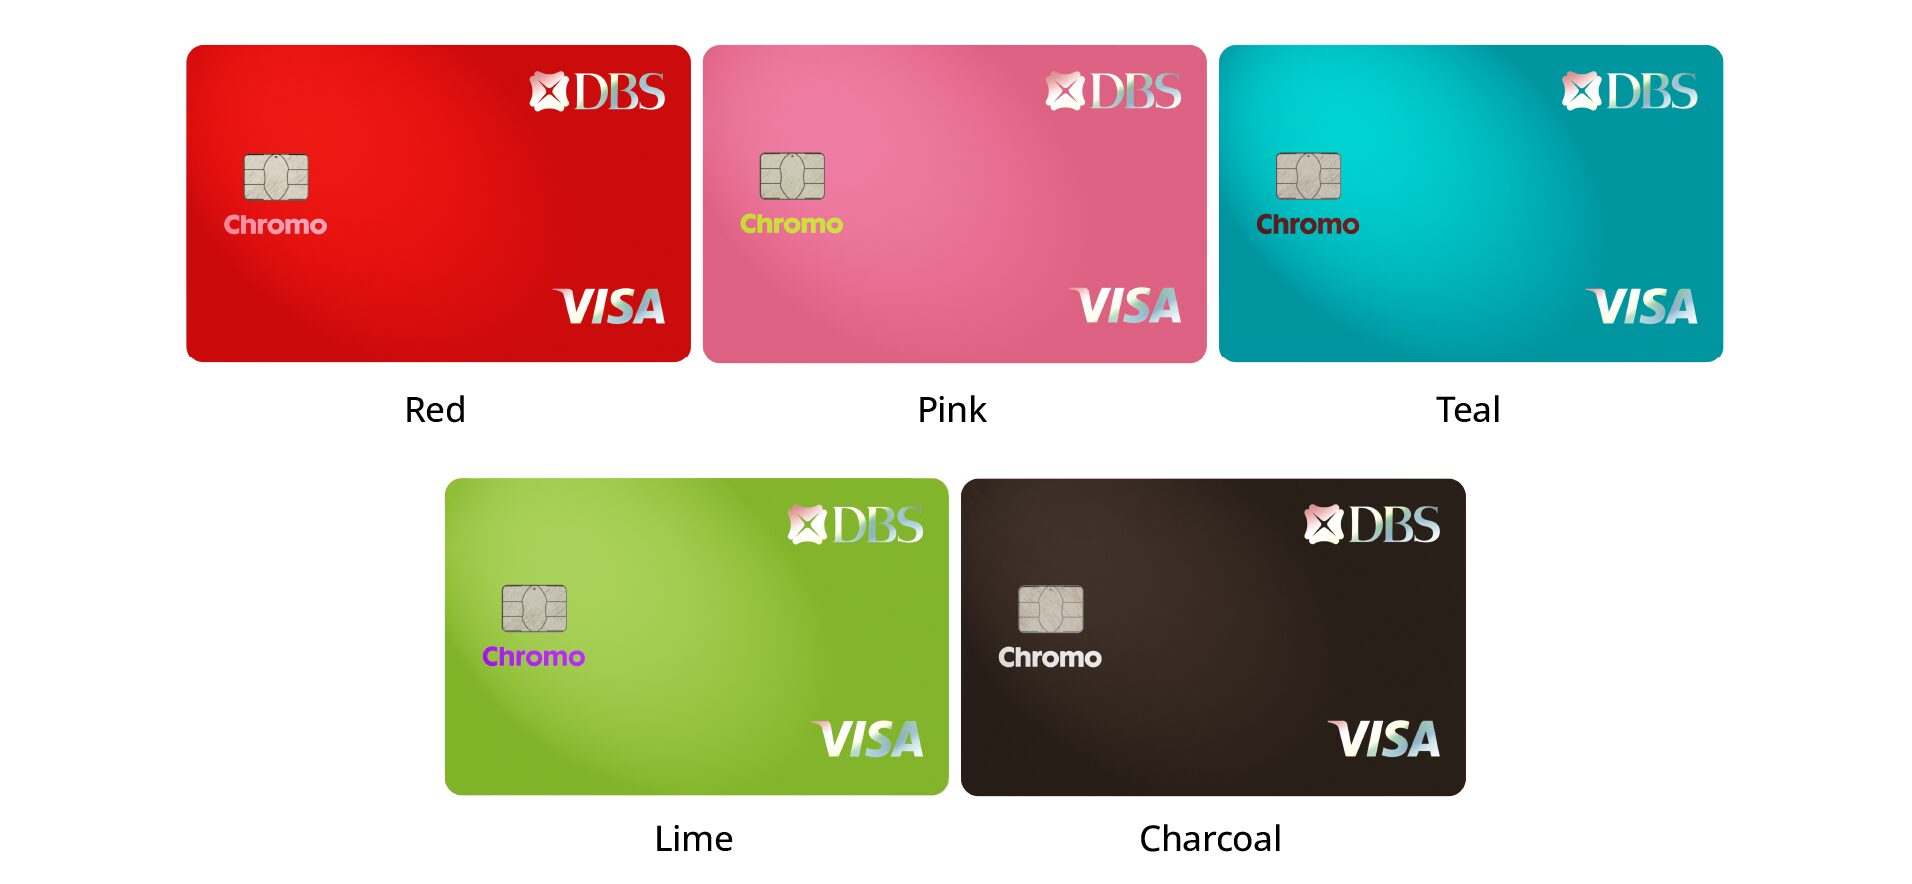
While it looks like something straight out of a My First Credit Card playset, this is indeed DBS’s chosen vessel to reach those aged 21-29. This penta-toned card offers a five-year annual fee waiver, no foreign currency (FCY) transaction fees (but no rewards for FCY spend), and the ability to request a new card colour every month for a nominal fee. No, really.
It also allows cardholders to choose between earning miles or cashback, though like most hybrid rewards cards, one of those options usually sucks.
Unfortunately, the poor cousin here is miles, with an underwhelming 1.3 mpd on all local spend. The alternative option of 5% cashback on a range of everyday categories is more compelling — but since the DBS Chromo Card wants to dabble in the miles space, that’s how I’m going to review it.
 DBS Chromo Card |
|
| 🦁 MileLion Verdict | |
| ☐ Take It ☐ Take It Or Leave It ☑ Leave It |
|
| What do these ratings mean? |
|
| Don’t let the marketing fool you — the DBS Chromo Card is a miles card in name only, and cardholders would be well advised to use it for cashback instead. | |
| 👍 The Good | 👎 The Bad |
|
|
| Full List of Credit Card Reviews | |
Overview: DBS Chromo Card
Let’s start this review by looking at the key features of the DBS Chromo Card.
| DBS Chromo Card |
|||
| Apply | |||
| Min. Income | S$30,000 p.a. | Points Validity | No expiry |
| Annual Fee | S$196.20 (5-year waiver) |
Min. Transfer | 5,000 DBS Points (10,000 miles) |
| Miles with Annual Fee | None | Transfer Partners | 3 |
| FCY Fee | None | Transfer Fee | S$27.25 |
| Local Earn | 1.3 mpd SGD only |
Points Pool? | Yes |
| FCY Earn | None | Lounge Access? | No |
| Special Earn | None | Airport Limo? | No |
| Cardholder Terms and Conditions |
|||
The DBS Chromo Card offers cardholders a choice of two rewards modes:
- Cashback
- Miles
Cashback is the default choice, but cardholders have the ability to toggle between earning miles or cashback via the DBS digibank app. A maximum of one switch can be made per calendar month.
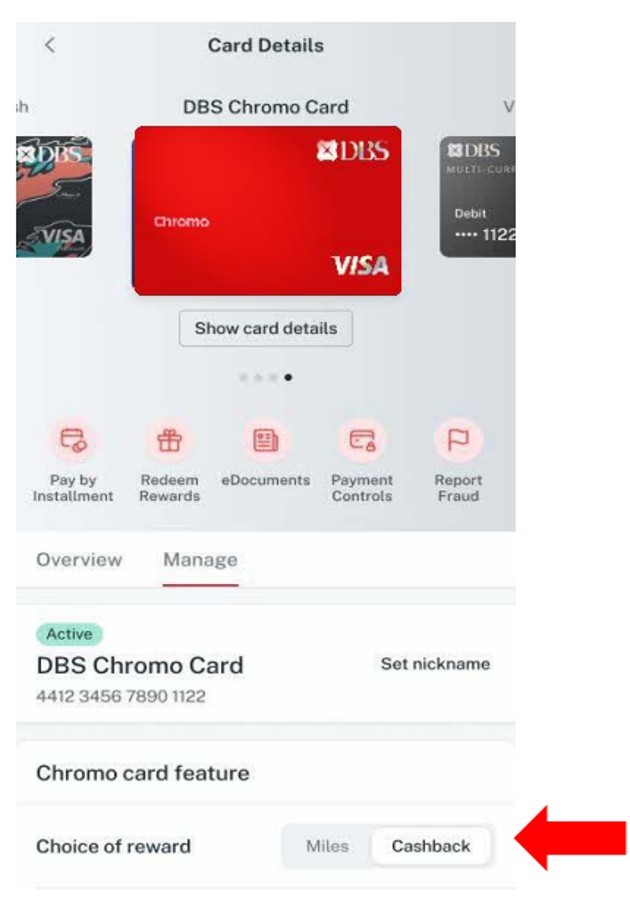
Naturally, I’ll be focusing on the miles option in this post, but for the sake of completeness, I’ll also outline how the cashback feature works at the end of this review — in my opinion, it’s actually the better choice for most people!
Cardholders can switch their reward preference for the previous month’s eligible spend by the 10th day of the following month. For example, your setting as of 10 October 2026 will determine how transactions from 1-30 September 2026 are treated.
This is great, because it allows you to spend first, decide later. If you didn’t manage to meet the minimum spend for bonus cashback in a given month, you can simply switch to miles mode by the 10th of the following month, and “salvage” the previous month’s spending.
How much must I earn to qualify for a DBS Chromo Card?
The DBS Chromo Card has a minimum income requirement of S$30,000 p.a.
But that’s not the main barrier to entry. The real restriction is that the DBS Chromo Card is only available to applicants aged 21-29 years old. You can apply as long as you haven’t crossed your 30th birthday (so 29 years and 364 days would be the absolute cutoff).
Don’t worry — no one breaks down your door to confiscate the card once you turn 30. You can keep the Chromo as long as you want after that, though once you cancel, you won’t be able to apply for it again.
However, the cashback rewards structure will change from the fourth month after your 30th birthday. I’ll address that later, when we talk about the cashback alternative.
How much is the DBS Chromo Card’s annual fee?
| Principal Card | Supp. Card | |
| First Five Years | Free | N/A |
| Subsequent Years | S$196.20 | N/A |
The DBS Chromo Card has an annual fee of S$196.20, which is waived for the first five years. It’s conjecture on my part, but I suspect it’ll be quite easy to get a fee waiver even after that.
Supplementary cards are currently not offered for the DBS Chromo Card.
What welcome offers are available?
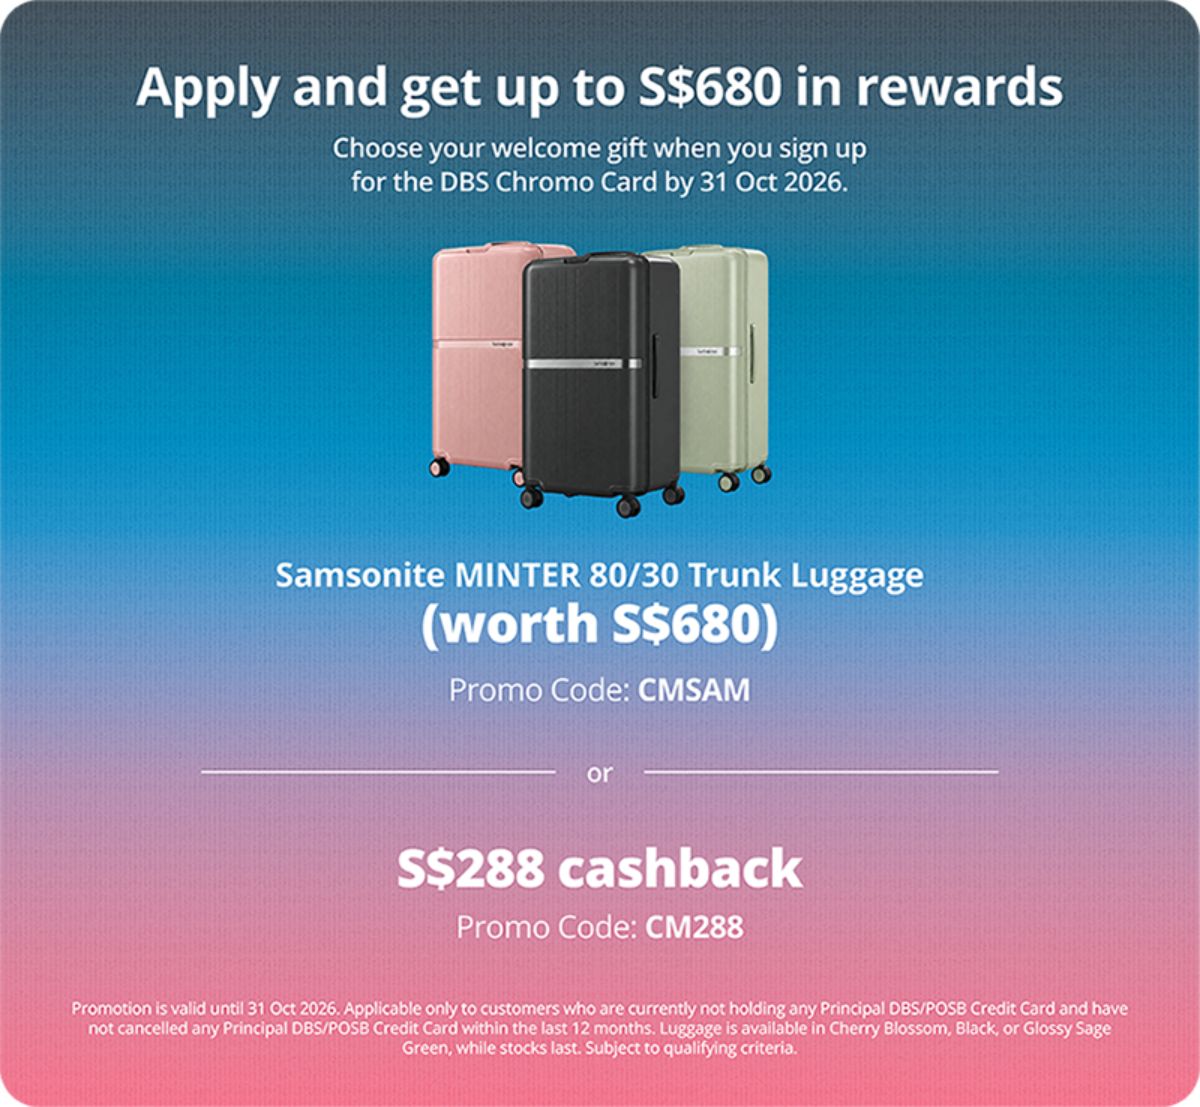
New-to-bank customers who apply for a DBS Chromo Card by 15 October 2026 can choose one of the following welcome gifts:
- S$350 Shopee voucher
- 22,000 Max Miles (worth S$396 via FlyAnywhere)
- Beats 360 headphones (worth S$349)
- S$320 cash
- Dyson Cool AM07 Tower Fan (worth S$499)
You must enter the promo code SINGSAVER when applying.
| ❓ New-to-bank customer definition |
|
A new-to-bank customer is defined as someone who:
|
A minimum spend of S$500 within the first 30 days of approval is required, and customers must have a valid DBS PayLah! account by the end of the qualifying spend period.
How many miles do I earn?
| 🇸🇬 SGD Spend | 🌎 FCY Spend | ⭐ Bonus Spend |
| 1.3 mpd | N/A | N/A |
SGD/FCY Spend
In miles mode, the DBS Chromo Card earns:
- 3.25 DBS Points for every S$5 spent in SGD (1.3 mpd)
- No rewards for FCY spend
There is no minimum spend necessary for miles mode, and no cap on the maximum number of miles you can earn.
1.3 mpd for local spend is pretty average, and the absence of any rewards for FCY spend is extremely disappointing.
| 💳 Earn Rates for Entry-Level General Spending Cards (Sorted by Sum of Local + FCY Spend) |
||
| Cards | Local Spend | FCY Spend |
 UOB PRVI Miles Card AMEX MC Visa |
1.4 mpd | 3 mpd IDR, MYR, THB, VND 2.4 mpd All Others |
 BOC Elite Miles Card Apply |
1.4 mpd | 2.8 mpd |
 HSBC TravelOne Card Apply |
1.2 mpd | 2.4 mpd |
 DBS Altitude Card AMEX Visa |
1.3 mpd | 2.2 mpd |
 OCBC 90°N Card MC Visa |
1.3 mpd | 2.1 mpd |
 Citi PremierMiles Card Apply |
1.2 mpd | 2.2 mpd |
 StanChart Journey Card Apply |
1.2 mpd | 2 mpd |
 Trust Freedom Card Apply via app with code 2GQEAM81 |
1.3 mpd | 1.3 mpd |
 AMEX KrisFlyer Ascend Apply |
1.2 mpd | 1.2 mpd |
 KrisFlyer UOB Credit Card Apply |
1.2 mpd | 1.2 mpd |
 AMEX KrisFlyer Credit Card Apply |
1.1 mpd | 1.1 mpd |
| DBS Chromo Card Apply |
1.3 mpd | N/A |
| ⚠️ What about DCC transactions? |
| If you make an overseas transaction and opt for DCC, the converted amount will count as local spend and qualify for rewards. However, you shouldn’t be opting for DCC in the first place, because the mark-ups involved would almost certainly outweigh the benefits. |
Given the numerous general spending cards with higher earn rates and similar income requirements, it’s difficult to see why anyone should be earning miles with the DBS Chromo Card — except in one scenario.
If you were originally intending to earn bonus cashback, but fell short of the minimum spend (unlike miles mode, cashback mode has a minimum spend), you’d only earn 1% cashback. In that case, I’d argue that 1.3 mpd is the superior option.
But this is really more about damage control than optimisation, and I don’t think anyone should set out with the goal of earning miles with the DBS Chromo Card.
What is the FCY fee?
While DBS normally has a 3.25% FCY fee, this does not apply to the DBS Chromo Card. All FCY transactions will be converted into SGD at the prevailing Visa rate, with no further mark-up.
| 💳 FCY Fees by Issuer and Card Network |
||
| Issuer | ↓ MC & Visa | AMEX |
| Standard Chartered | 3.5% | N/A |
| American Express | N/A | 3.25% |
| Citibank | 3.25% | N/A |
| DBS | 3.25% 0% for Chromo |
3.25% |
| DCS | 3.25% | N/A |
| HSBC | 3.25% | N/A |
| Maybank | 3.25% | N/A |
| OCBC | 3.25% | N/A |
| UOB | 3.25% 0% for EVOL/Singtel-UOB |
3.25% |
| BOC | 3% | N/A |
| CIMB | 3% 0% for Founders Card |
N/A |
| ICBC | 2.5% | N/A |
| Chocolate | 0% | N/A |
| GXS Bank | 0% | N/A |
| Maribank | 0% | N/A |
| Trust | 0% | N/A |
Is this enough to make up for the lack of rewards on FCY spend? Not really. Even if avoiding FCY transaction fees were the primary concern, you could still earn:
- 1.3 mpd or 3% stockback with the Trust Freedom Card
- 1.5% cashback with the Mari Credit Card
- 0.5-1% cashback with the UOB EVOL Card
Transaction date or posting date?
Like all DBS credit cards, minimum spend is tracked by transaction date, not posting date. A transaction made on 30 June which posts on 2 July will count towards June’s minimum spend and bonus cap (for cashback mode).
When are DBS Points credited?
With the DBS Chromo Card, cashback and miles aren’t credited when the transaction posts. That makes sense, when you consider the mechanism — remember, you have until the 10th of the following month to decide whether you want to earn miles or cashback.
Instead, base cashback and miles will be credited within 30 days following the end of the calendar month.
Bonus cashback on the top two spend categories will be credited within 60 days following the end of the calendar month.
How are DBS Points calculated?
Some people get anxious when they read in the T&Cs that DBS Points are awarded in S$5 blocks. That’s understandable, given how UOB’s S$5 earning blocks result in a lot of lost miles from rounding, especially for small transactions.
But DBS’s calculations aren’t nearly as penalising. Here’s how the DBS Points on the DBS Chromo Card are calculated:
| Local Spend | Divide transaction by 5 and multiply by 3.25. Round down to the nearest whole number |
| FCY Spend |
N/A |
Notice how the transaction is not rounded down to the nearest S$5; instead, it’s divided by 5 straight away. This means the minimum spend to earn points is not S$5, but rather S$1.54.
To illustrate the point, here’s how the DBS Chromo Card compares to the OCBC 90°N Card. While both have the same headline earn rate of 1.3 mpd, there are certain transaction sizes for which the Chromo comes out ahead.
 DBS Chromo Card 1.3 mpd |
OCBC 90°N Card 1.3 mpd |
|
| S$5 | 6 miles 1.2 mpd |
7 miles ✅1.4 mpd |
| S$9.99 | 12 miles ✅ 1.2 mpd |
7 miles 0.7 mpd |
| S$15 | 18 miles 1.2 mpd |
20 miles ✅1.33 mpd |
| S$19.99 | 24 miles ✅ 1.2 mpd |
20 miles 1 mpd |
| S$25 | 32 miles 1.28 mpd |
33 miles ✅1.32 mpd |
| S$29.99 | 38 miles ✅ 1.27 mpd |
33 miles 1.1 mpd |
| Headline Earn Rate Actual Earn Rate | ||
If you’re an Excel geek, here are the formulas you need to calculate points:
| Local Spend | =ROUNDDOWN ((X/5)*3.25,0) |
| FCY Spend |
N/A |
| Where X= Amount Spent |
|
For the full list of formulas that banks use to calculate credit card points, refer to these articles:
What transactions aren’t eligible for DBS Points?
The DBS Chromo Card will not earn points on the following transactions:
- Amaze transactions (not that it matters here, because only Mastercards can be paired with Amaze)
- Charitable donations
- Education
- Government institutions and services
- Hospitals
- Insurance
- Real estate agents and managers
- Top-ups of prepaid accounts e.g. GrabPay
- Utility bills
A full list of transactions that do not earn DBS Points can be found at point 2.6 of the DBS Rewards Programme’s T&Cs.
What about CardUp?
 |
| Enjoy a 2.3% fee on your first payment of up to S$5,000 on a Visa card, with the promo code MILELION |
DBS Points will be awarded for CardUp transactions at a rate of 1.3 mpd.
Fees for Visa cards range from 2.25% to 2.45%, depending on payment type. Given the 1.3 mpd earn rate, this is equivalent to buying miles at 1.69 to 1.84 cents each.
This is definitely on the high side, and anyway, the rule with CardUp is to use the highest-earning general spending card you can get (which at the S$30,000 income bracket would be the UOB PRVI Miles at 1.4 mpd).
What do I need to know about DBS Points?
| ❌ Expiry | ↔️ Pooling | 💰 Transfer Fee |
| No expiry | Yes | S$27.25 per conversion |
| ⬆️ Min. Transfer | ✈️ No. of Partners | ⏱️ Transfer Time |
| 5,000 DBS Points (10,000 miles) |
3 | 1-2 working days (KrisFlyer) |
Expiry
DBS Points earned on the DBS Chromo Card never expire.
Pooling
DBS Points pool across cards for the purposes of redemption. If you have 10,000 DBS Points on the DBS Chromo Card and 5,000 DBS Points on the DBS Woman’s World Card, you can redeem 15,000 DBS Points at one shot and pay a single conversion fee.
However, DBS Points are not pooled when it comes to card cancellations. If I have a DBS Chromo Card and DBS Woman’s World Card and decide to cancel the former, I’ll need to transfer my points out before cancelling or forfeit them.
Transfer partners
DBS offers three frequent flyer partners (Qantas Points transfers were removed in September 2026), but in reality it’s more like two, since AirAsia Rewards offers relatively poor value and is generally best avoided.
| Frequent Flyer Programme | Conversion Ratio (DBS Points : Miles) |
 |
5,000 : 10,000 |
 |
5,000 : 10,000 |
 |
500: 1,500 |
Transfer fee
Transfers cost S$27.25 each, regardless of how many points are transferred.
Transfer blocks
A minimum conversion of 10,000 miles is required for KrisFlyer and Asia Miles.
The DBS Chromo Card is not eligible for DBS’s “auto-conversion programme”, which automatically converts DBS Points to KrisFlyer miles each calendar quarter in blocks of 500 points, for a flat fee of S$43.60 per membership year.
How does the DBS KrisFlyer Miles Auto Conversion Programme work?
However, because DBS Points pool, you can sign up for the auto-conversion programme on a participating card (Altitude, Insignia, Treasures Black Elite), and use it as a conduit to automatically convert DBS Points earned on the Chromo Card.
Transfer times
DBS quotes a points conversion time of 1-2 weeks, but transfers are usually completed much faster:
- KrisFlyer: 1-2 working days
- Asia Miles: 5 working days
If you need your points credited instantly, you can do so via Kris+. 100 DBS Points can be instantly transferred to 170 KrisPay miles, which can then be converted to KrisFlyer miles at a 1:1 ratio with no fees.
 |
| S$5 for new Kris+ Users |
| Get S$5 when you sign up with code W644363 and make your first transaction |
However, those 100 DBS Points would normally have earned you 200 KrisFlyer miles, so you effectively take a 15% haircut. Therefore, I wouldn’t recommend taking this option, unless you need a small top-up to redeem a flight, or need to cash out an orphan DBS Points balance (<5,000 DBS Points).
Do remember that transfers are a two-step process:
- Transfer DBS Points to KrisPay miles
- Transfer KrisPay miles to KrisFlyer miles
Do not forget the second step! If you wait more than 21 days, or spend any of the converted KrisPay miles via Kris+, the entire balance will be stuck in the Kris+ app, and can no longer be transferred to KrisFlyer.
KrisPay miles expire after six months, and can only be spent at a relatively poor value of 100 miles = S$1.
Other card perks
Change your card colour every month
Have you ever stared at your credit card and lamented that life would be infinitely better if you only had the ability to change its colour every month?
No?
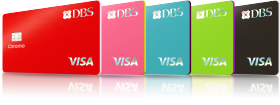
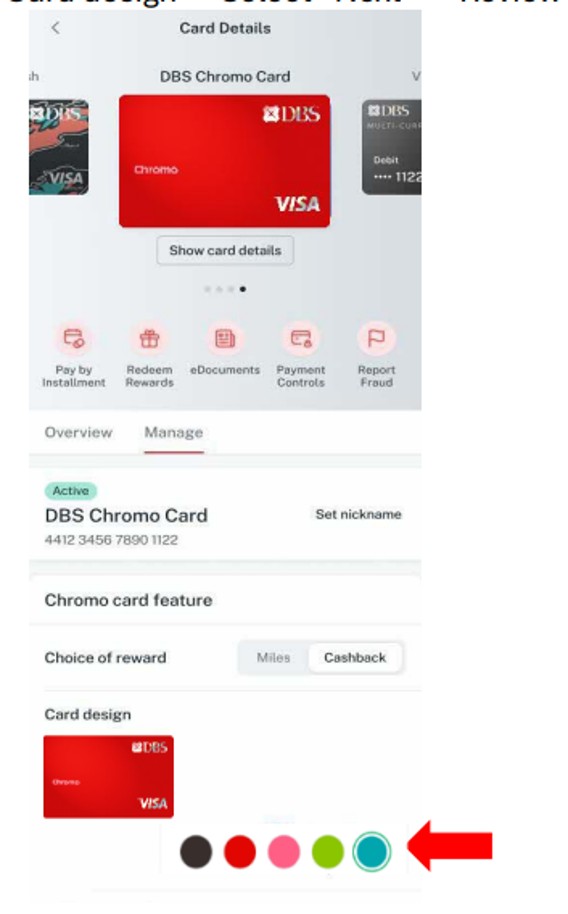
Well, the DBS Chromo Card allows you to do it anyway. Cardholders can change their card design once per month via the DBS digibank app, choosing from a veritable optical migraine of colours. There’s a S$10.90 fee for each change.
Mind you, this is the same DBS which proudly boasts of its eco-friendly credentials and efforts to reduce its environmental footprint. How does that gel with someone replacing their card every month? Beats me.
But if it’s any consolation for the polar bears, I highly doubt anyone will bother to do this. It’s not like these cards are head-turners, anyway. They look like the credit card equivalent of a mood ring, or staring at paint swatches.
Bonus interest with DBS Multiplier
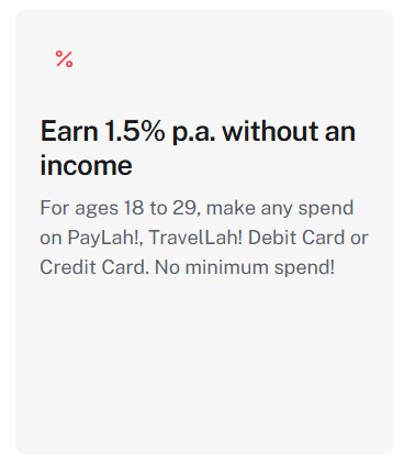
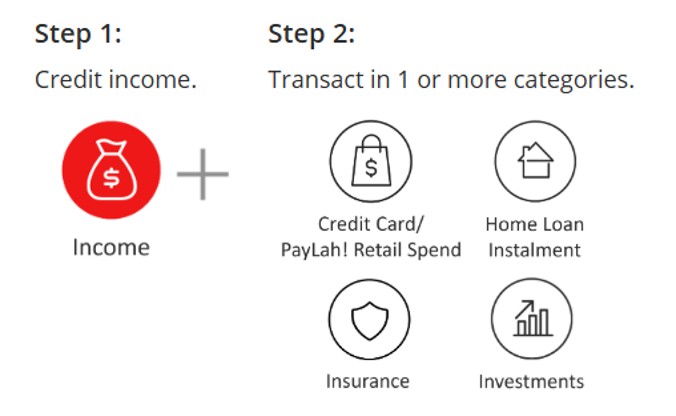
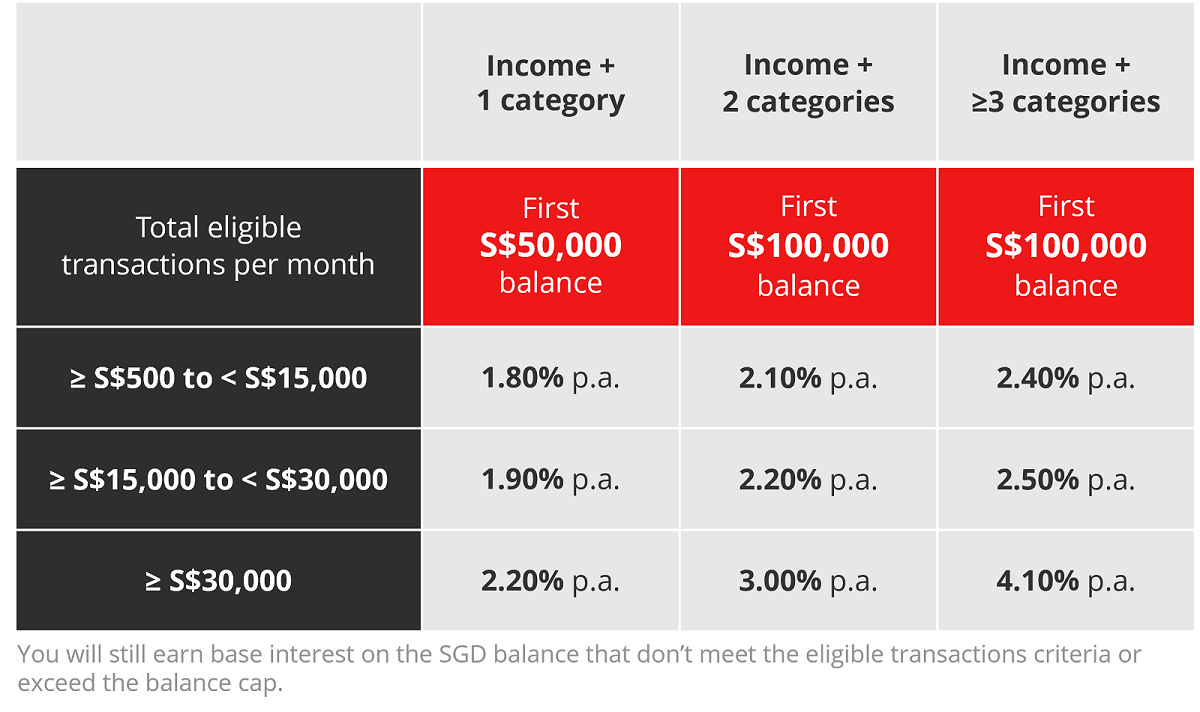
Customers aged 29 and below — the target group for the Chromo — can earn 1.5% p.a. on the first S$50,000 by spending any amount on their DBS Chromo Card (or other DBS cards, for that matter), PayLah! or TravelLah! debit card. No income crediting is required.
Otherwise, they can unlock higher bonus interest by crediting their salary and completing any of the following activities.
What about cashback mode?
If you have one takeaway from this review so far, it’s that you shouldn’t be using the DBS Chromo Card in miles mode. The earn rates are simply too mediocre to bother with.
I actually reckon that cardholders would get more value from cashback mode instead.
Cashback earn rates and caps
In cashback mode, the DBS Chromo Card earns:
- 1% base cashback, with no minimum spend
- 4% bonus cashback on two bonus categories, with a minimum spend of S$500 per calendar month
There are two cashback caps to note here:
- Bonus cashback is capped at S$30 per category, per calendar month
- Base + bonus cashback is capped at S$150 per calendar month
What this means is that the cap will be hit if you spend S$750 in each of the two bonus categories, and a maximum of S$9,000 overall on the card.
This also means that you can use the DBS Chromo Card purely for bonus-eligible spending. The minimum spend to earn bonus cashback is S$500 per month, which is less than the spending cap for cashback of S$750 per category. Therefore, you could spend anywhere from S$500 to S$1,500 at an effective rate of 5% cashback.
Cashback bonus categories
A total of six bonus categories are available, but what’s interesting is that you don’t need to select specific bonus categories. Instead, the DBS Chromo Card will automatically select the two with the highest eligible spending each month.
| 💳 DBS Chromo Card Bonus Categories |
|
| Category | Examples |
| 🍽️ Dining |
|
| 📽️ Entertainment |
|
| 👗 Shopping |
|
| 🚕 Transport |
|
| ✈️ Travel |
|
| 💆 Wellness |
|
| The detailed list of qualifying MCCs for each category can be found in the T&Cs. | |
If you’re a disorganised person who uses the DBS Chromo Card everywhere, this is a good feature, because it helps to maximise your cashback.
However, if you’re disciplined about where you use the DBS Chromo Card, this is a bad feature, because it limits you to earning bonuses on two out of six categories.
What counts towards minimum spend?
The S$500 minimum spend consists of all local and foreign currency transactions (even though the latter don’t earn rewards), except for ineligible transactions such as charitable donations, education, hospitals, insurance premiums, government services, prepaid top-ups and utility bills.
How does the DBS Chromo Card change after 30?
You can only apply for the DBS Chromo Card if you’re aged below 30, but you can still keep the card after turning 30.
However, the rewards structure will change from the fourth month after your 30th birthday. For example, if your 30th birthday is 30 January 2028, the benefit change date will be 1 May 2028.
| Up to 30 years 3 months | From 30 years 4 months | |
| Miles | 1.3 mpd | 1.3 mpd |
| Base Cashback | 1% | 1.7% |
| Bonus Cashback | 4% on 2 categories with min. S$500 spend per c. month | None |
| Cashback Cap | S$30 per category, S$150 per c. month | None |
| FCY Fee | None | None |
| Rewards for FCY Spend? | No | No |
At this point, the DBS Chromo Card becomes a simple 1.3 mpd or 1.7% cashback card, with no minimum spend or caps. The zero FCY fee benefit continues, but you still don’t earn rewards for FCY spending.
A 1.7% cashback rate is actually very decent, particularly since the DBS Chromo Card is a Visa. The only other card at the 1.7% cashback level — temporarily upsized to 2% until 31 January 2027 — is the UOB Absolute Cashback Card, which faces limited acceptance as an AMEX. The DCS Ultimate Cashback Mastercard does offer 2% cashback, though it is capped at S$200 per month.
| 💳 General Spending Cashback Cards (Without Min. Spends) |
||
| Annual Fee | SGD Spend | |
 DCS Ultimate Cashback Apply |
S$130.80* (1st Year Free) |
2% Cashback capped at S$200 per c. month |
 UOB Absolute Cashback Apply |
S$196.20 (1st Year Free) |
2%^ Ends 31 Jan 27 |
| DBS Chromo Card Apply |
S$196.20 (5 Years Free) |
1.7% |
 BOC Visa Infinite Apply |
S$381.50 (1st Year Free) |
1.6% |
 Citi Cash Back+ Card Apply |
S$196.20 (1st Year Free) |
1.6% |
 OCBC Infinity Cashback Apply |
S$196.20 (1st Year Free) |
1.6% |
 ICBC Chinese Zodiac Card Apply |
S$150 (3 Years Free) |
1.6% |
 Maybank FC Barcelona Card Apply |
S$130.80 (2 Years Free) |
1.6% |
 AMEX True Cashback Card Apply |
S$174.40 (1st Year Free) |
1.5% |
 Mari Credit Card Apply via app with code 7KZX22QY |
None | 1.5% |
 SC Simply Cash Card Apply |
S$196.20 (1st Year Free) |
1.5% |
| Trust Freedom Card Apply via app with code2GQEAM81 |
None | 1.5% |
| *Billed as S$10.90 per month ^Limited-time promotion for in-person contactless spend, valid until 31 January 2027. 1.7% for online spending |
||
Conclusion
| DBS Chromo Card Apply |
|
| 🦁 MileLion Verdict | |
| ☐ Take It ☐ Take It Or Leave It ☑ Leave It |
Does the new DBS Chromo Card deserve a place in your wallet?
Not as a miles card. If you qualify for a DBS Chromo Card, you’re also eligible for far better miles cards, with superior earn rates and perks. I’m taking the stance of a miles user, hence my “Leave It” recommendation.
Not as a zero FCY fee card. There are other cards with zero FCY fees that don’t force you to give up rewards entirely.
As a local spending cashback card? Well, 5% cashback with a minimum spend of S$500 and an effective cashback cap of S$75 is a decent proposition, though the Maybank XL Cashback Card is probably the better choice. If we were reviewing this from a cashback perspective, then it’d definitely garner at least a “Take It Or Leave It” recommendation.
In fact, I’d say the best thing about the Chromo is the flexibility to choose your reward after the month is completed, though that also means your cashback and miles take 30-60 days to arrive.
But hey, if you’ve ever wanted to change your card colour every month, that dream can finally come true.
What do you make of the DBS Chromo Card?
