
HeyMax First is HeyMax’s “Fly Now, Earn Later” facility, which allows members to borrow Max Miles to redeem a flight or hotel stay, then earn back the deficit at their own pace.
The facility involves two types of fees:
- a membership fee, which is waived for the first year
- an access fee, which is paid when withdrawing miles, and fully refunded when the borrowed miles are returned
Previously, the access fee could only be paid via PayNow, but HeyMax is now adding a credit card payment option.
And that creates a very interesting opportunity to buy credit card miles from just 0.73 cents each — though one has to wonder how long this will last.
HeyMax First adds credit card payment option
 HeyMax First |
|||
| Tier | Miles Pool | Membership Fee (FYF) |
Access Fee (Per Mile) |
| Silver | 30K | Free | 3¢ |
| Gold | 100K | S$299 | 2.7¢ |
| Platinum | 300K | S$699 | 2.5¢ |
| Reserve | 1M | S$1,999 | 2.3¢ |
Every HeyMax member has a complimentary HeyMax First Silver membership by default. They can choose to upgrade to a higher tier if they wish — the first year’s membership fee is waived — in order to enjoy a bigger miles pool and lower access fee.
When borrowing miles from their miles pool, HeyMax First members have the option of paying the access fee through credit card:
- A non-refundable processing fee of 3% applies
- Payments will code as MCC 5311 (Department Stores)
- Only Singapore-issued credit cards are accepted
- The access fee will be refunded via PayNow, even if users paid by card
That last part is where it all comes together. You pay by credit card…and get refunded in cash. I think you know where this is going.
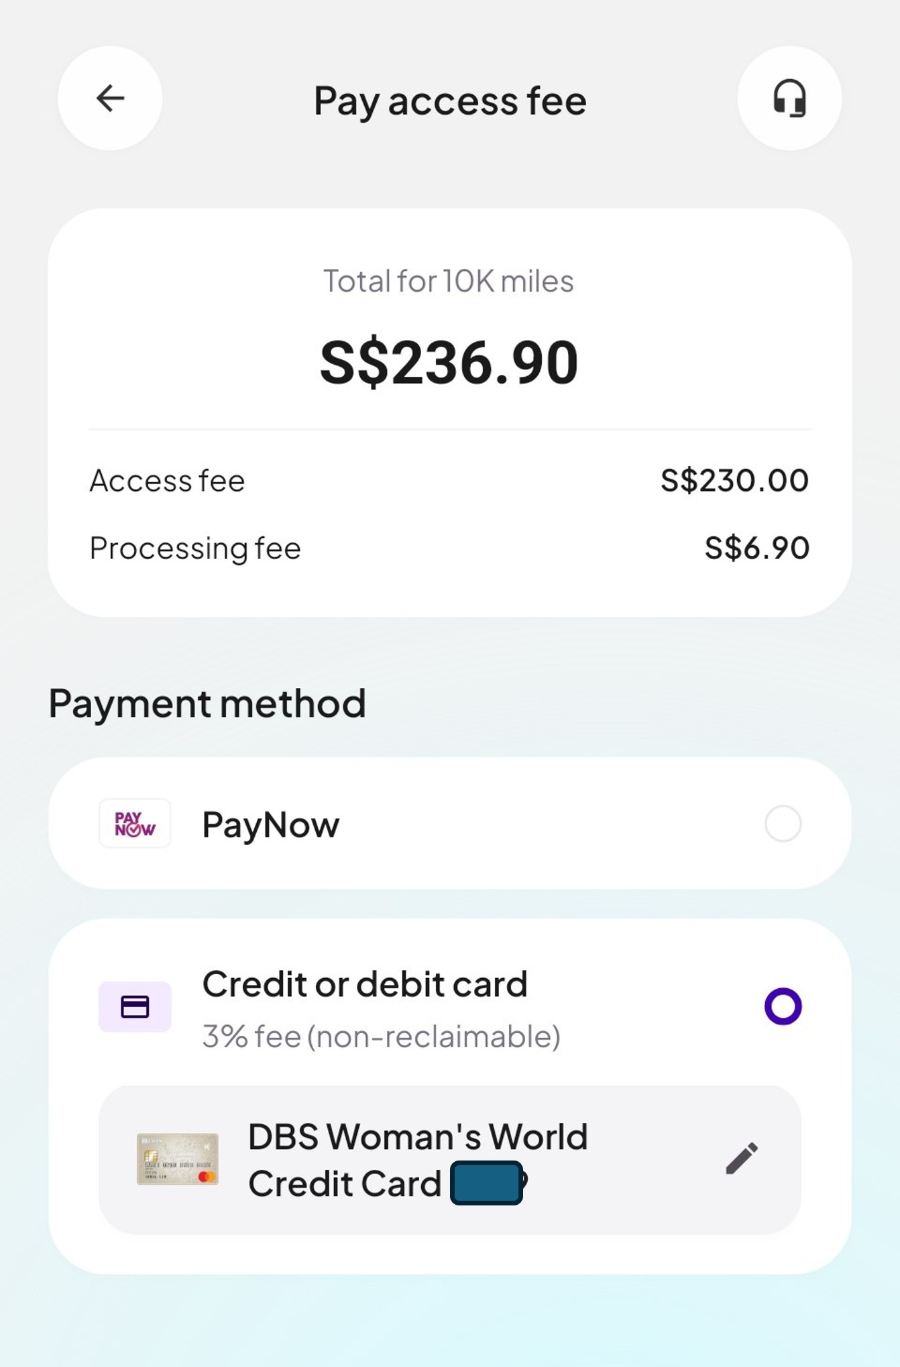
Here’s an illustration:
- You borrow 30,000 Max Miles with your HeyMax First Silver membership
- The access fee is S$900 (30,000 x 3 cents), which becomes S$927 after the 3% processing fee
- Pay with a card that earns 4 mpd on MCC 5311 and you earn 3,708 miles (S$927 x 4)
- Once you repay the Max Miles, the S$900 access fee is refunded
- Your total out-of-pocket cost is the non-refundable processing fee of S$27, for which you earned 3,708 miles
- The overall cost is 0.73 cents per mile
That’s an interesting way of buying miles, to say the least. It’s far cheaper than any bill payment service out there, whether CardUp, or Citi PayAll, or SC EasyBill.
| Platform | Admin Fee Earn Rate |
Cost Per Mile |
| HeyMax First |
3% 4 mpd |
From 0.73¢ |
 Tax Payment Facility |
1.9% 1-2 mpd |
From 0.95¢ |
 |
2.5% 1-2 mpd |
From 1.25¢ |
 |
2.25-2.59% 1.2-2 mpd |
From 1.38¢ |
 |
2.3% Ends 31 Dec 26 1.2-1.6 mpd |
From 1.44¢ |
 Payment Facility |
1.6-1.8% Ends 31 Oct 26 1 mpd |
From 1.60¢ |
Not an infinite miles hack
Before you get too excited, I want to point out that this is not an infinite miles hack, because you cannot repay HeyMax First with borrowed Max Miles. You can only repay the deficit with Max Miles earned from other sources.
This matters because every time you borrow and repay, your earned Max Miles get used up, while the borrowed ones stay in your account. In other words, the total amount you can borrow and immediately repay is capped by how many Max Miles you’ve earned.
Here’s an example. Suppose I’ve earned 50,000 Max Miles so far, and I use HeyMax First to borrow a further 30,000 Max Miles. Since I have enough earned Max Miles, I can repay the full amount immediately.
| Earned Max Miles | Borrowed Max Miles | Total Balance | Amount Owed |
| 50,000 | 0 | 50,000 | 0 |
| Borrow 30,000 Max Miles | |||
| 50,000 | 30,000 | 80,000 | 30,000 |
| Repay 30,000 Max Miles | |||
| 20,000 | 30,000 | 50,000 | 0 |
My total balance reverts to 50,000, but now, only 20,000 of those are earned Max Miles. The other 30,000 are from HeyMax First, so they can’t be used to repay future drawdowns.
Now suppose I borrow another 30,000 Max Miles. This time, I can only repay 20,000 immediately, because that’s all the earned Max Miles I have left.
| Earned Max Miles | Borrowed Max Miles | Total Balance | Amount Owed |
| 20,000 | 30,000 | 50,000 | 0 |
| Borrow 30,000 Max Miles | |||
| 20,000 | 60,000 | 80,000 | 30,000 |
| Repay 20,000 Max Miles | |||
| 0 | 60,000 | 60,000 | 10,000 |
I still owe 10,000 Max Miles, which I must earn from other sources before I can fully repay the drawdown. Until then, the remaining access fee stays with HeyMax.
So while there’s no limit on how often you can borrow, there is a “speed limit” of sorts. Once your earned Max Miles run out, you either wait until you’ve earned more, or accept that your access fee will have to remain parked with HeyMax in the meantime.
Is it better to be a lower-tier HeyMax First member?
Here’s an interesting, somewhat counterintuitive quirk. If your goal is to buy credit card miles, HeyMax First Silver is actually the best tier to be on.
The cost per mile is the same at every tier. You pay a 3% processing fee and earn 4 mpd, so the result is 0.73 cents per mile regardless of the access fee rate.
What differs is how much card spend each earned Max Mile can support. Since earned Max Miles are the bottleneck, you want each one to generate as much card spend as possible. That’s what a higher access fee does.
| Example: Draw 10,000 Max Miles | |||
| Tier | Access Fee | Card Spend (incl. 3% fee) |
Miles Earned (4 mpd) |
| Silver | 3¢ |
S$309 | 1,236 |
| Gold | 2.7¢ | S$278 | 1,112 |
| Platinum | 2.5¢ | S$258 | 1,030 |
| Reserve | 2.3¢ | S$237 | 948 |
As the table shows, Silver gets you about 30% more miles than Reserve, for the same number of Max Miles drawn.
What about the bigger miles pool that higher tiers offer? That helps, but only if you’re willing to park cash with HeyMax. If your plan is to borrow and repay immediately, the pool size doesn’t matter. The limit remains your earned Max Miles, and a bigger pool just means fewer, larger drawdowns.
But if you’re willing to borrow more than you can immediately repay, the pool determines how far ahead of your earnings you can get. Once your earned Max Miles are depleted, the pool caps your outstanding drawdown at any one time, and therefore how much card spend you can generate before you have to stop and earn more Max Miles through other means.
| Tier | Miles Pool Access Fee |
Max. Access Fee (+3% processing fee) |
Miles Earned (4 mpd) |
| Silver | 30K 3¢ |
S$927 | 3,708 |
| Gold | 100K 2.7¢ |
S$2,781 | 11,124 |
| Platinum | 300K 2.5¢ |
S$7,725* | 30,900 |
| Reserve | 1M 2.3¢ |
S$23,690* | 94,760 |
| *This would have to be spread out over more than one month, as the monthly 4 mpd caps aren’t sufficient to support this | |||
Of course, you’ll have to weigh whether you’re comfortable parking that amount of cash with HeyMax, plus the opportunity cost of what those funds could be generating elsewhere.
What cards to use for HeyMax First?
| 💳 Best Cards for HeyMax First (MCC 5311) |
||
| Card | Earn Rate | Remarks |
 Citi Rewards Card Apply |
4 mpd | Max S$1K per s. month Review |
 DBS Woman’s World Card Apply |
4 mpd | Max S$1K per c. month Review |
 HSBC Revolution Card Apply |
4 mpd | Max S$1K per c. month Review |
 Maybank XL Rewards Card Apply |
4 mpd | Min. S$500, max S$1K per c. month Review |
 OCBC Rewards Card Apply |
4 mpd | Max S$1.1K per c. month Review |
 UOB Lady’s Card Apply |
4 mpd | Max S$1K per c. month, must choose Fashion as bonus category Review |
 UOB Lady’s Solitaire Apply |
4 mpd | Max S$750 per c. month, must choose Fashion as bonus category Review |
 UOB Preferred Visa Apply |
4 mpd | Max S$600 per c. month Review |
 KrisFlyer UOB Credit Card Apply |
2.4 mpd | Min. S$1K SIA Group spend per m. year. No cap Review |
| C. month = Calendar month | S. month = Statement month | M. Year = Membership Year | ||
HeyMax First codes as MCC 5311, one of the most common bonus categories — and no doubt why HeyMax chose it in the first place.
I count no fewer than eight 4 mpd options, with a combined monthly cap of S$7,450. So in theory, you could buy up to 29,800 miles per month on your credit cards at the 0.73 cents figure we worked out earlier (S$217 total).
It could even be more if you qualify for the 6 mpd rate with the UOB Lady’s Cards (deposit S$10K in a Lady’s Savings Account) or the 8 mpd rate with the HSBC Revolution (deposit S$50K in a HSBC EGA).
After the 4 mpd caps are exhausted, you could switch to the KrisFlyer UOB Credit Card and buy KrisFlyer miles at 1.21 cents each (3% fee, uncapped 2.4 mpd earn rate with a minimum spend of S$1,000 on Singapore Airlines, Scoot, or KrisShop in a membership year).
Of course, this assumes you have enough earned Max Miles to keep repaying your drawdowns. Putting S$7,450 through HeyMax First at the Silver tier would require borrowing and repaying about 241,000 Max Miles each month, so for most people, the real limit will be their earned Max Miles balance, rather than their card bonus caps.
It doesn’t stop with miles. You could use this to clock the minimum spend necessary for bonus interest with bank accounts:
- S$500 on the UOB Lady’s Card/Lady’s Solitaire for UOB One
- S$500 on the OCBC Rewards Card for OCBC 360
- S$500 on the Maybank XL Rewards Card for Maybank SaveUp
I’m less familiar with the cashback options, but I believe the Citi SMRT Card offers 5% cashback on online spending with a minimum spend of S$500 per month, capped at S$600 cashback per membership year. That allows you to earn a 2% spread.
This is great, but…
On the one hand, this is exciting stuff.
On the other, I also wonder whether it’s going to be one of those “fly too close to the sun” moments for HeyMax.
Think about who’s actually paying for this party. HeyMax isn’t losing money, since the 3% processing fee should more or less cover its card acceptance costs. You’re not losing money; buying miles at 0.73 cents is a sweet deal. The one footing the bill is the bank, which awards 4 mpd on what is, for all intents and purposes, a round trip of cash.
Banks take a dim view of, um, let’s call it “inorganic spend”, and I’m pretty sure this will raise some red flags. Most card T&Cs contain some variation of a clause that allows the bank to claw back rewards on transactions it doesn’t consider genuine purchases of goods and services, and it’s hard not to imagine this being one of them.
It’s something we’ve seen many times before. Whenever a payment channel becomes a way of manufacturing miles, banks usually respond by excluding the merchant. The only question is how long it takes.
My bigger concern is that this may get HeyMax blacklisted altogether. Banks generally exclude merchants by name rather than specific product, so if this escalates, it won’t just be the HeyMax First access fee that stops earning miles. Voucher purchases through HeyMax could be caught in the crossfire too, which would be a steep price to pay for a few months of cheap miles.
We’ll see.
Conclusion
The HeyMax First access fee can now be paid through credit card, with a 3% processing fee. While the processing fee is non-refundable, the access fee is refunded in cash, which effectively lets you buy miles at 0.73 cents each with a 4 mpd card. That handily beats every other bill payment service out there.
But this feels like the sort of thing that won’t last very long, and I just hope that it doesn’t result in unintended consequences.
