
HeyMax First is a “Fly Now, Earn Later” facility, which allows HeyMax users to borrow Max Miles and redeem a flight or hotel stay today, then earn back the deficit at their own pace.
It’s a novel solution that flips the script on earning and burning. Traditionally, you earn miles first, and hope that a redemption opportunity will arise later — all the while praying that devaluations and programme changes don’t shift the goalposts. HeyMax First takes the uncertainty out of the situation by allowing users to redeem first, then earn back the miles later.
After an invitation-only beta, HeyMax First is now open to everyone. All HeyMax users receive a complimentary Silver tier membership by default, while those who want to borrow more miles with a smaller deposit can upgrade to a paid tier, with the first year’s membership fee waived for a limited time.
While HeyMax First offers a useful way of bridging the gap between earning and burning, just as interesting are the “off-label” uses, such as generating cheap credit card miles, or clocking minimum spend towards sign-up bonuses or bonus interest.
We’ll cover these later in the guide, together with everything you need to know about HeyMax First.
Overview: HeyMax First
 |
|
| Get a HeyMax account Get 200 Max Miles when you sign up for a HeyMax account and complete one transaction |
|
| Join HeyMax First | |
| FAQs |
Let’s start by clarifying one thing: joining HeyMax First does not mean you get a lump sum deposit into your Max Miles account. Rather, you trigger the withdrawals when you want, in the quantity that you want.
In that sense, HeyMax First is conceptually similar to a credit line of Max Miles. You can draw from it when needed, then replenish it as you earn Max Miles through shopping at partner merchants, buying vouchers, spending on the Chocolate Visa/Trust Freedom Card, converting yuu Points, referring friends etc.
HeyMax First has four tiers of membership, which differ in terms of credit line — referred to as a “miles pool” — membership fee, and access fee.
 HeyMax First |
|||
| Tier | Miles Pool | Membership Fee (FYF) |
Access Fee (Per Mile) |
| Silver | 30K | Free | 3¢ |
| Gold | 100K | S$299 | 2.7¢ |
| Platinum | 300K | S$699 | 2.5¢ |
| Reserve | 1M | S$1,999 | 2.3¢ |
Membership fee
All HeyMax users receive a complimentary Silver membership, which is free for life.
The membership fee for Gold, Platinum and Reserve ranges from S$299 to S$1,999 per year. It will be waived for the first year for all new joiners, but must be paid from the second year onwards.
Access fee
In addition to the membership fee, HeyMax users will pay a deposit — known as an “access fee” — every time they wish to draw miles from their miles pool.
The access fee ranges from 2.3 to 3 cents per mile, and withdrawals can be made in blocks of 10,000 Max Miles. For example, a Gold member has a pool of 100,000 miles to draw from. He can withdraw 50,000 Max Miles by paying a fee of S$1,350 (50,000 x 2.7 cents each).
Here’s the crucial bit: unlike the membership fee, the access fee is refundable.
The access fee can be reclaimed in blocks of 10,000 Max Miles, as you earn them from day-to-day HeyMax activity. Going back to our Gold member example, once he earns 10,000 Max Miles, he can reclaim S$270 (10,000 x 2.7 cents each) of the outstanding S$1,350 access fee.
Therefore, the membership fee is the only unavoidable component (though remember, it’s waived in the first year).
| ⚠️ Not an automatic deduction |
| HeyMax will not automatically deduct Max Miles to repay the deficit. Users will instead initiate the repayment (and refund of the access fee) from their app. This gives them the flexibility of deciding when to repay. |
How are HeyMax First fees paid?
| Credit Card* | PayNow | |
| Membership Fee | ✅ No fee MCC 5311 |
❌ |
| Access Fee | ✅ Non-refundable 3% fee MCC 5311 |
✅ |
| *Only Singapore-issued credit cards are accepted | ||
Membership fee
Membership fees are paid via credit card. You’ll be prompted to provide your card details at the time of joining, but the membership fee will only be deducted from the second year onwards.
Access fee
Access fees can be paid via PayNow or credit card. If you choose the latter, a non-refundable processing fee of 3% applies.
As we’ll see later on in the section on off-label uses, you might actually want to pay that processing fee!
How do I borrow or return Max Miles?
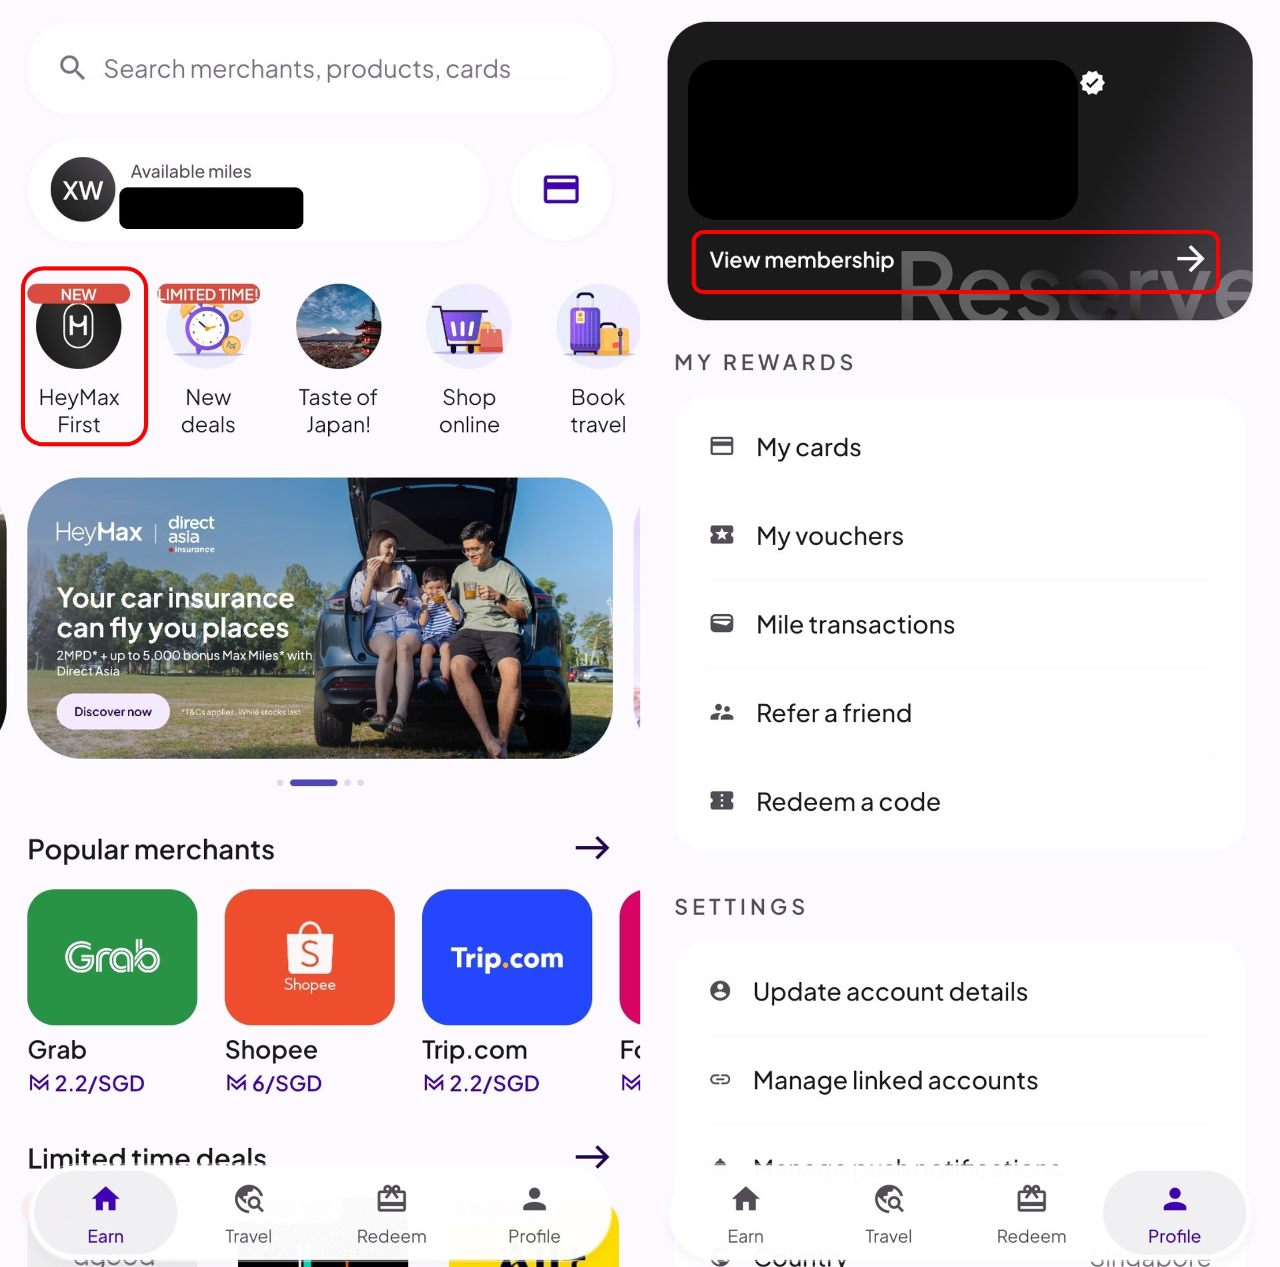
To borrow or return Max Miles, open the HeyMax app and tap on the HeyMax First badge on the home screen. Alternatively, you can tap on Profile > HeyMax First.
Withdrawals
To borrow miles, tap on Draw Miles, select the number of miles you wish to withdraw (in blocks of 10,000) and pay the access fee through PayNow or a credit card.
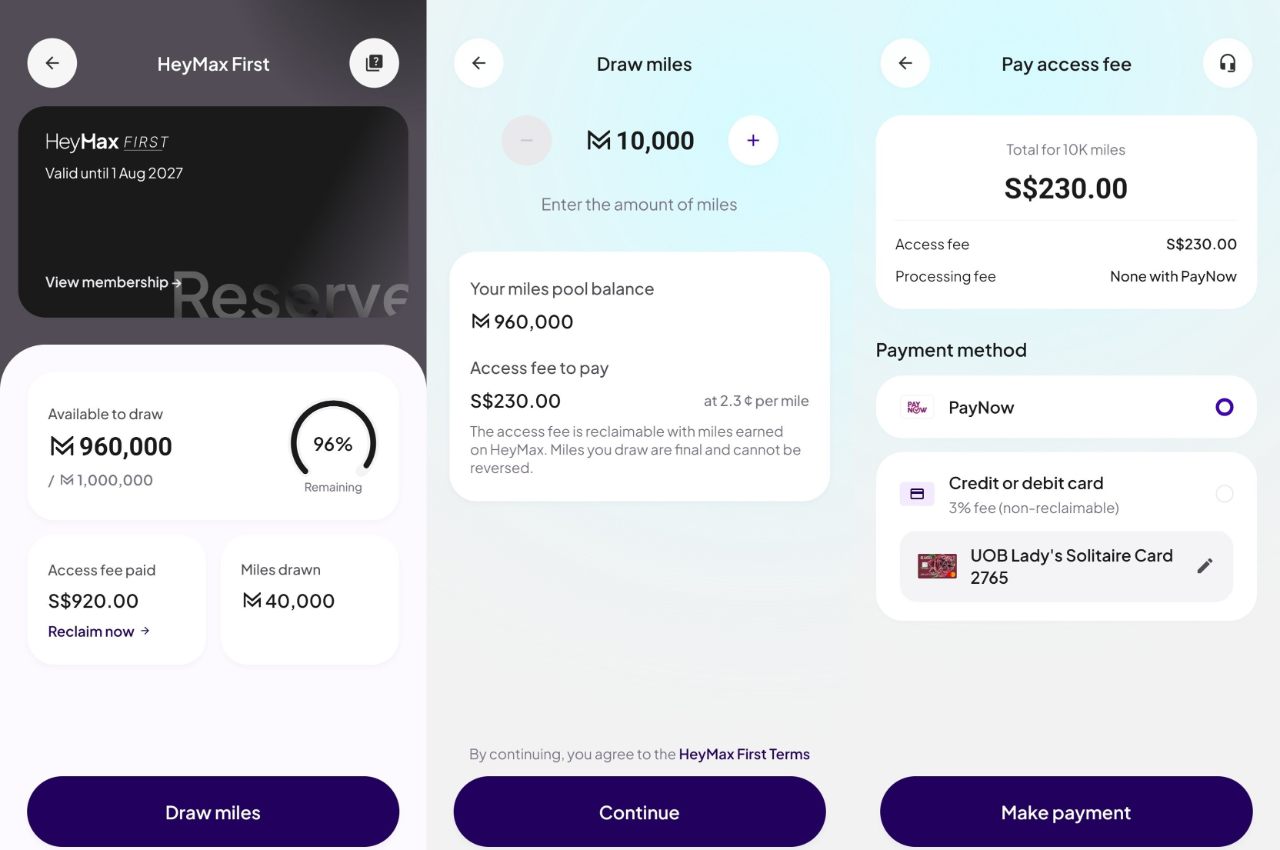
Miles will be deposited instantly upon payment.
Repayment
To return Max Miles, tap on Reclaim Now, then select the number of miles you wish to repay (in blocks of 10,000) and confirm.
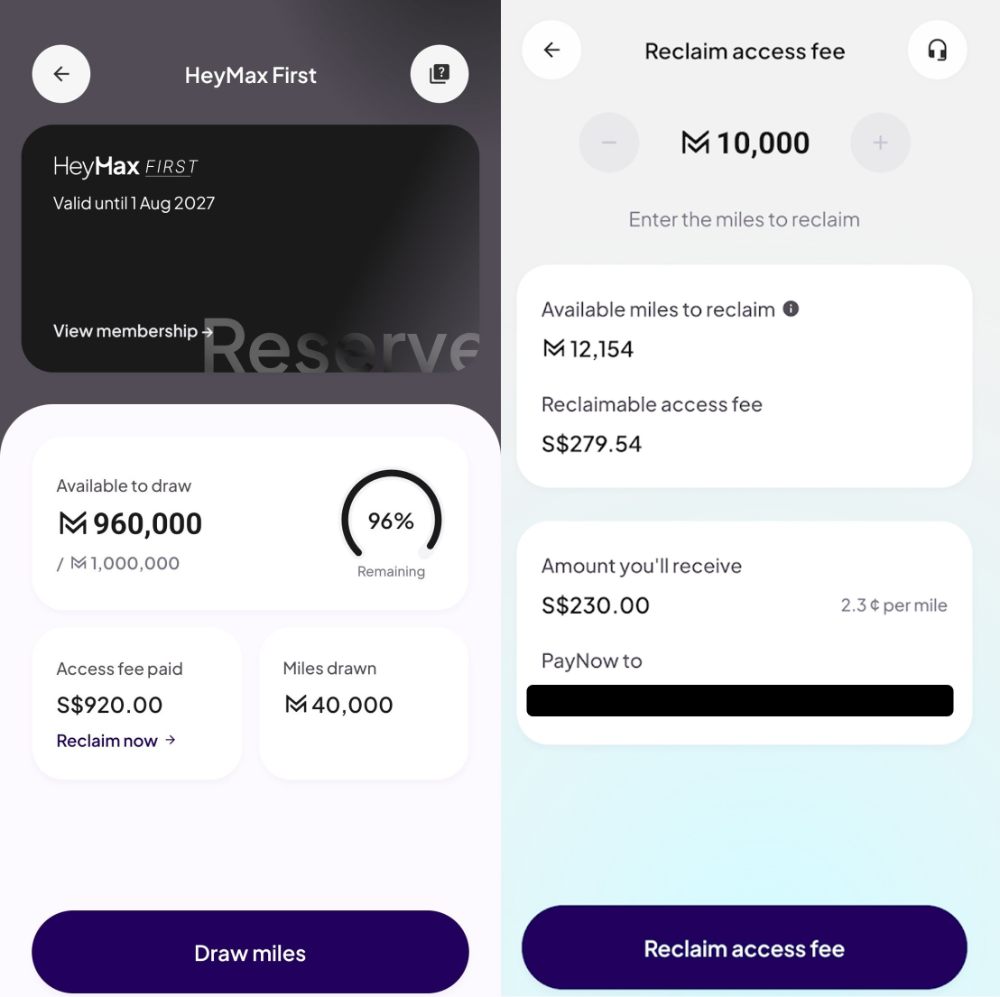
The access fee will be refunded via PayNow within a few hours.
Is there a deadline to repay the Max Miles?
Not really. You can reclaim your access fee so long as you’re a HeyMax user.
There’s no deadline. Reclaim eligibility persists indefinitely — even if you don’t renew a paid tier or pause your HeyMax activity. Your outstanding access fees remain reclaimable for as long as you’re a HeyMax user.
-HeyMax
That said, you don’t want to wait too long, because your funds with HeyMax won’t be generating any interest.
In case you were worried, making a withdrawal does not “lock you in” to your current tier. If your membership year is ending and you still have an outstanding balance, there is no obligation to renew at the same tier level.
For example, suppose I’m a Platinum member with an outstanding drawdown of 200,000 Max Miles. At the end of my membership year, instead of renewing Platinum and paying a further membership fee of S$699, I can downgrade to the free Silver tier. When I repay my outstanding balance, the access fee will be refunded at the original Platinum rate of 2.5 cents per mile.
Of course, I won’t be able to withdraw any further miles from the Silver tier’s pool of 30,000 Max Miles until my outstanding balance is less than 30,000, but at least I won’t be forced to renew at the same Platinum tier.
What happens if you don’t repay the Max Miles?
That’s up to you, really, but HeyMax First is structured in a way that repaying is in your own interest.
Why? Because the access fee is set at a level which makes the cost per mile unattractively high for buying. So you’re perfectly at liberty to draw down 1,000,000 miles and disappear into the night, but is paying 2.3 cents per Max Mile really a good deal? I don’t think so.
When would HeyMax First be useful?

HeyMax First is designed for moments when you find yourself thinking “I wish I had more Max Miles”.
Consider the case of a couple planning their honeymoon, but find themselves short of the necessary miles. With HeyMax First, they can get the miles upfront, lock in the tickets, then gradually earn back the shortfall, knowing their plans are already secured.
However, what I see as the key benefit of HeyMax First is having a credit line on standby, ready for drawdown when opportunities arise.
Award space suddenly appears
Award space often follows a famine and feast pattern — there may be long periods where nothing good is available, and then a brief moment where a lot of seats suddenly pop up.
When that happens, it’s helpful to have a ready stash of miles that you can quickly convert to snap up awards.
Devaluations
If a loyalty programme announces an upcoming devaluation, you might want to lock in some flights at the current prices. Again, having a credit line would be useful for doing so, if you’re just shy of the miles required for a redemption, or if there’s a particular sweet spot award you’d like to book several of.
Transfer bonuses
HeyMax occasionally offers transfer bonuses, which can be opportunities to get outsized value for your Max Miles.
For instance, HeyMax recently ran an uncapped 20% transfer bonus for converting Max Miles to Accor Live Limitless, which worked out to a value of 3.56 cents per Max Mile (based on the previous 1:1 ratio, which has now been devalued to 3:2). I know of many people who drained their accounts for this, and probably wish they had more Max Miles handy!
What can you do with Max Miles?
Max Miles can be converted to the following airline and hotel programmes, mostly at a 1:1 ratio. All conversions are free of charge.
| ✅ HeyMax Transfer Partners All 1:1 unless otherwise stated |
|
| ✈️ Airlines | |
|
|
| 🏨 Hotels | |
|
|
Max Miles can also be redeemed via the FlyAnywhere feature at 1.8 cents each. FlyAnywhere is a useful feature that I’m fond of, but in the context of HeyMax First, borrowing Max Miles at 2.3-3 cents only to cash them out at 1.8 cents doesn’t really make sense.
What are the “off-label” uses for HeyMax First?
While HeyMax First is fundamentally about borrowing Max Miles, the fact that you can pay the access fee with a credit card gives rise to some interesting “off-label” uses!
Buying credit card miles
The HeyMax First access fee will always be refunded by PayNow, regardless of the original payment method.
In other words, you pay via credit card, and get refunded in cash. Yes, there’s a non-refundable 3% processing fee, but the miles you earn could far outweigh that.
Access fee payments code as MCC 5311 Department Stores, which is eligible to earn up to 4 mpd with a wide range of credit cards. You could even earn 6 mpd with the UOB Lady’s Card, paired with the Lady’s Savings Account (LSA), or 8 mpd with the HSBC Revolution, paired with the Everyday Global Account (EGA).
| 💳 Best Cards for HeyMax First (MCC 5311) |
||
| Card | Earn Rate | Remarks |
 HSBC Revolution Card With EGA Apply |
8 mpd |
Max S$1.2K per c. month. Min. S$50K ADB in EGA Review |
 UOB Lady’s Card With LSA Apply |
6 mpd |
Max S$1K per c. month, must choose Fashion as bonus category. Min. S$10K ADB in LSA Review |
 UOB Lady’s Solitaire With LSA Apply |
6 mpd | Max S$750 per c. month, must choose Fashion as bonus category. Min. S$10K ADB in LSA Review |
 Citi Rewards Card Apply |
4 mpd | Max S$1K per s. month Review |
 DBS Woman’s World Card Apply |
4 mpd | Max S$1K per c. month Review |
| HSBC Revolution Card Regular Apply |
4 mpd |
Max S$1K per c. month Review |
 Maybank XL Rewards Card Apply |
4 mpd | Min. S$500, max S$1K per c. month Review |
 OCBC Rewards Card Apply |
4 mpd | Max S$1.1K per c. month Review |
| UOB Lady’s Card Regular Apply |
4 mpd |
Max S$1K per c. month, must choose Fashion as bonus category Review |
| UOB Lady’s Solitaire Regular Apply |
4 mpd | Max S$750 per c. month, must choose Fashion as bonus category Review |
 UOB Preferred Visa Apply |
4 mpd | Max S$600 per c. month Review |
 KrisFlyer UOB Credit Card Apply |
2.4 mpd | Min. S$1K SIA Group spend per m. year. No cap Review |
| C. month = Calendar month | S. month = Statement month | M. Year = Membership Year | ||
Here’s an illustration:
- You borrow 30,000 Max Miles with your HeyMax First Silver membership
- The access fee is S$900 (30,000 x 3 cents), which becomes S$927 after the 3% processing fee
- Pay with a card that earns 4 mpd on MCC 5311 and you earn 3,708 miles (S$927 x 4)
- Once you repay the Max Miles, the S$900 access fee is refunded
- Your total out-of-pocket cost is the non-refundable processing fee of S$27, for which you earned 3,708 miles
- The overall cost is 0.73 cents per mile
Depending on which card you use, the cost per mile could even be as low as 0.36 cents.
| Card Earn Rate | Processing Fee | Cost Per Mile |
| 2.4 mpd | 3% | 1.21¢ |
| 4 mpd | 3% | 0.73¢ |
| 6 mpd | 3% | 0.49¢ |
| 8 mpd | 3% | 0.36¢ |
This is far cheaper than any bill payment service out there, whether CardUp, or Citi PayAll, or SC EasyBill.
| Platform | Admin Fee Earn Rate |
Cost Per Mile |
| HeyMax First |
3% Up to 8 mpd |
From 0.36¢ |
 Tax Payment Facility |
1.9% 1-2 mpd |
From 0.95¢ |
 |
2.5% 1-2 mpd |
From 1.25¢ |
 |
2.25-2.59% 1.2-2 mpd |
From 1.38¢ |
 |
2.3% Ends 31 Dec 26 1.2-1.6 mpd |
From 1.44¢ |
 Payment Facility |
1.6-1.8% Ends 31 Oct 26 1 mpd |
From 1.60¢ |
Meeting the minimum spend for sign-up bonuses or bonus interest
Because HeyMax First is treated like any other retail spend, you can use it to clock the minimum spend for credit card sign-up bonuses. This works because there’s no reversal of the original credit card charge when the access fee is refunded (you get cash refunded into your bank account).
HeyMax First would also count as eligible card spending for bonus interest with certain bank accounts, such as:
- Spending S$500 on the UOB Lady’s Card/Lady’s Solitaire for bonus interest with UOB One
- Spending S$500 on the OCBC Rewards Card for bonus interest with OCBC 360
- Spending S$500 on the Maybank XL Rewards Card for bonus interest with Maybank SaveUp
It’s worth a reminder that your funds will be tied up with HeyMax until you earn enough Max Miles to reclaim the access fee, so you’ll want to be strategic about how much you charge.
What’s the difference between earned and borrowed Max Miles?
Before you get too excited, I want to point out that HeyMax First is not an infinite miles hack, because you cannot repay HeyMax First with borrowed Max Miles.
Outstanding HeyMax First balances can only be repaid with earned Max Miles, which refers to Max Miles acquired from other sources. This includes (but is not limited to):
- Buying HeyMax vouchers
- Converting Chocolate Finance returns into miles
- Converting Atome Points
- Converting yuu Points
- Spending on the Chocolate Visa Card
- Spending on the Trust Freedom Card
- Shopping through the HeyMax portal
- Referring friends to HeyMax
- Reserving tables with HeyMax
Basically, every time you borrow and repay, your earned Max Miles get used up, while the borrowed ones stay in your account. In other words, the total amount you can borrow and immediately repay is capped by how many Max Miles you’ve earned.
Here’s an example. Suppose I’ve earned 50,000 Max Miles so far, and I use HeyMax First to borrow a further 30,000 Max Miles. Since I have enough earned Max Miles, I can repay the full amount immediately.
| Earned Max Miles | Borrowed Max Miles | Total Balance | Amount Owed |
| 50,000 | 0 | 50,000 | 0 |
| Borrow 30,000 Max Miles | |||
| 50,000 | 30,000 | 80,000 | 30,000 |
| Repay 30,000 Max Miles | |||
| 20,000 | 30,000 | 50,000 | 0 |
My total balance reverts to 50,000, but now, only 20,000 of those are earned Max Miles. The other 30,000 are from HeyMax First, so they can’t be used to repay future drawdowns.
Now suppose I borrow another 30,000 Max Miles. This time, I can only repay 20,000 immediately, because that’s all the earned Max Miles I have left.
| Earned Max Miles | Borrowed Max Miles | Total Balance | Amount Owed |
| 20,000 | 30,000 | 50,000 | 0 |
| Borrow 30,000 Max Miles | |||
| 20,000 | 60,000 | 80,000 | 30,000 |
| Repay 20,000 Max Miles | |||
| 0 | 60,000 | 60,000 | 10,000 |
I still owe 10,000 Max Miles, which I must earn from other sources before I can fully repay the drawdown. Until then, the remaining access fee stays with HeyMax.
So while there’s no limit on how often you can borrow, there is a “speed limit” of sorts. Once your earned Max Miles run out, you either wait until you’ve earned more, or accept that your access fee will have to remain parked with HeyMax in the meantime.
What tier should you choose?
If your goal is to buy credit card miles, HeyMax First Silver is actually the best tier to be on.
The cost per mile is the same at every tier. You pay a 3% processing fee and earn 4 mpd, so the result is 0.73 cents per mile regardless of the access fee rate.
What differs is how much card spend each earned Max Mile can support. Since earned Max Miles are the bottleneck, you want each one to generate as much card spend as possible. That’s what a higher access fee does.
| Example: Draw 10,000 Max Miles | |||
| Tier | Access Fee | Card Spend (incl. 3% fee) |
Miles Earned (4 mpd) |
| Silver | 3¢ |
S$309 | 1,236 |
| Gold | 2.7¢ | S$278 | 1,112 |
| Platinum | 2.5¢ | S$258 | 1,030 |
| Reserve | 2.3¢ | S$237 | 948 |
As the table shows, Silver gets you about 30% more miles than Reserve, for the same number of Max Miles drawn.
What about the bigger miles pool that higher tiers offer? That helps, but only if you’re willing to park cash with HeyMax. If your plan is to borrow and repay immediately, the pool size doesn’t matter. The limit remains your earned Max Miles, and a bigger pool just means fewer, larger drawdowns.
But if you’re willing to borrow more than you can immediately repay, the pool determines how far ahead of your earnings you can get. Once your earned Max Miles are depleted, the pool caps your outstanding drawdown at any one time, and therefore how much card spend you can generate before you have to stop and earn more Max Miles through other means.
| Tier | Miles Pool Access Fee |
Max. Access Fee (+3% processing fee) |
Miles Earned (4 mpd) |
| Silver | 30K 3¢ |
S$927 | 3,708 |
| Gold | 100K 2.7¢ |
S$2,781 | 11,124 |
| Platinum | 300K 2.5¢ |
S$7,725* | 30,900 |
| Reserve | 1M 2.3¢ |
S$23,690* | 94,760 |
| *This would have to be spread out over more than one month, as the monthly 4 mpd caps aren’t sufficient to support this | |||
Of course, you’ll have to weigh whether you’re comfortable parking that amount of cash with HeyMax, plus the opportunity cost of what those funds could be generating elsewhere.
What happens when you renew HeyMax First?
Renewing your HeyMax First membership does not give you a fresh batch of miles per se. Rather, it allows you to continue using the credit line that you were granted when you initially registered.
For example, John is a Gold member who has drawn down 40,000 Max Miles from his 100,000 Max Miles credit line. Renewing his membership for a further year does not mean he has a 200,000 Max Miles credit line now. He’s still a Gold member, with a net credit line of 60,000 Max Miles to draw from.
How do upgrades and downgrades work?
HeyMax First members have the option to upgrade to a higher tier, or downgrade to a lower one.
Upgrades
Upgrades can be performed at any time.
Members will have access to the larger miles pool immediately, and any outstanding access fees can be reclaimed at the rate which was originally paid, with the earliest drawdown returned first.
If you’re within the first year fee waiver period
If you upgrade within the first year, the first year membership fee waiver extends to the new tier as well (i.e. there is no upgrade fee).
For example:
- John joined HeyMax First as a Gold member on 1 August 2026, and makes a drawdown of 40,000 Max Miles
- On 15 October 2026, he upgrades to Platinum, with no upgrade fee (as he’s still within his first year free period)
- He then makes a further drawdown of 60,000 Max Miles
- When the time comes to reclaim the access fee, 40,000 Max Miles will be reclaimed at the Gold rate of 2.7 cents per mile, and 60,000 Max Miles at the Platinum rate of 2.5 cents per mile
If you’re beyond the first year fee waiver period
If you upgrade after the first year, you will need to pay the difference in membership fee.
For example:
- John has completed his first year as a Gold member, and has an existing drawdown of 40,000 Max Miles
- In his second membership year, he upgrades to Platinum, and pays an additional S$400 membership fee (difference between S$299 and S$699)
- He then makes a further drawdown of 60,000 Max Miles
- When the time comes to reclaim the access fee, 40,000 Max Miles will be reclaimed at the Gold rate of 2.7 cents per mile, and 60,000 Max Miles at the Platinum rate of 2.5 cents per mile
Downgrades
Unlike upgrades, downgrades cannot be performed mid-year.
Members can choose a lower tier from the next renewal. Any outstanding access fees can be reclaimed at the rate which was originally paid, with the earliest drawdown returned first.
For example:
- John is a Gold member with a drawdown of 50,000 Max Miles
- He can downgrade to become a Silver member at the next renewal
- When the time comes to reclaim the access fee, 50,000 Max Miles will be reclaimed at the Gold rate of 2.7 cents per mile
What’s the catch?
With HeyMax First, you’re basically making an interest-free loan to HeyMax, in return for upfront miles.
The quantum of the loan depends on the extent of the drawdown, but could potentially reach as high as S$23,000, for a Reserve member who maxes out his miles pool.
| Tier | Miles Pool Access Fee |
Maximum Drawdown Cost |
| Silver | 30,000 3.0¢ |
S$900 |
| Gold | 100,000 2.7¢ |
S$2,700 |
| Platinum | 300,000 2.5¢ |
S$7,500 |
| Reserve | 1,000,000 2.3¢ |
S$23,000 |
Therefore, you need to weigh the utility of having miles now, versus the opportunity cost of tying up your funds with HeyMax. It’s also worth remembering that repayments are in blocks of 10,000 Max Miles, which limits the rate at which you can recover your access fee.
Furthermore, because you’re making a loan, you’ll need to evaluate the “credit risk” of HeyMax. Do you believe it will be a viable business long enough for you to claim your access fee back? As far as I know, the access fee is not custodised, so if the worst happens, you might not be able to recover it.
Conclusion
|
|
| Get 200 Max Miles when you sign up for a HeyMax account and complete one transaction | |
| Get a HeyMax account |
|
| Join HeyMax First |
HeyMax First is an innovative “fly now, earn later” scheme that gives you the Max Miles you need to redeem a trip today, and lets you worry about replenishing your balance later.
Used correctly, it can be a powerful tool, especially for time-sensitive opportunities like award space drops, transfer bonuses, or looming devaluations. Having a credit line of miles on standby can make the difference between snagging a great redemption and missing out entirely.
But for many members, the off-label uses may be even more compelling. Paying the access fee by credit card lets you buy miles for as little as 0.36 cents each, far cheaper than any bill payment platform. It’s also a handy way of clocking minimum spend for sign-up bonuses or bonus interest.
That said, it’s not a free lunch. You’re effectively extending an interest-free loan to HeyMax, and the opportunity cost (plus platform risk) shouldn’t be ignored. Your ability to recover that cash is also limited by how quickly you earn Max Miles, so don’t draw down more than you’re comfortable parking with HeyMax.

Spend more time and effort on traditional miles or better yet, cash.
Redemption flights are rarely for urgent events like family emergencies, health, death, birth etc. I wouldn’t borrow anything, whether $ or miles, for any non-urgent flight. Especially when I have to pay $ first just to borrow the miles! Probably I would fly budget or not go at all. There’s always another time.
It’s a good idea. My issue is that the heymax ecosystem is not extensive enough for high spenders to make 1 million miles in a short time. Obviously I am not going to buy a few hundred thiusands in vouchers or apply enough credit cards to cover the “loan” of 1 million miles.
Precisely my thoughts. Why borrow when paying back the miles might be difficult or take a long time? Not repaying the miles would be the same as purchasing the miles at 2.3+ cpm. Repaying the miles over years is an-interest free loan to the lender. Maybe the best scenario is to borrow a small number of miles to enable redemption of existing miles in a flyer program that is difficult to access with SG-based cards, like maybe aeroplan. But I’d prefer to just wait for the next sale to buy directly and either not travel or choose another option for… Read more »
Don’t even see Aeroplan on the list
Trying out Heymax First today, and now trying to transfer Max Miles to Qatar … so far system error (asked to try again later). Will update again when successful.
PS: previously successfully transferred Max Miles (earned the traditional way) to Qatar, so the pipeline works that way.
Finally managed to get it done, after raising ticket with HeyMax team reg the error