
Welcome to the 2026 edition of the S$120K Credit Card Showdown, my annual look at the finest pieces of plastic — or metal — that money can buy. S$120K cards come with hefty annual fees, so before you hop on board, you need to have a game plan for extracting maximum value.
This is now the ninth iteration of this guide, and it’s safe to say that the landscape has changed tremendously since the inaugural edition was published in 2017. Given the nerfs that S$120K cards have suffered over the past decade, can they still justify their price tags?
Let’s find out.
The S$120K candidates
Here are the seven cards that will be competing in this year’s S$120K showdown.
| 💳 S$120K Candidates | |
 AMEX Platinum Reserve Apply |
 Citi Prestige Card Apply |
 DBS Vantage Card Apply |
 Maybank Visa Infinite Apply |
 OCBC VOYAGE Apply |
 SC Visa Infinite Apply |
 UOB Visa Infinite Metal Card Apply |
|
There are other cards with similar income requirements, such as the CIMB Visa Infinite, but I don’t include them because they earn cashback instead of miles. I also exclude the UOB Lady’s Solitaire Metal Card because it’s by invitation only.
The AMEX Platinum Charge and Standard Chartered Beyond Card are also not included because their annual fees (S$1,744 and S$1,635 respectively) are nearly triple that of the S$120K segment. It’s not a fair fight — these cards offer way more benefits, but you’d expect them to!
This year, I’ve removed the HSBC Visa Infinite, which has not been accepting applications since September 2024. I included it in the 2025 edition in the hope that a relaunch might be imminent, but it’s now been two years with no news, so I’d rather focus on cards you can actually get.
Otherwise, the line-up is the same as 2025’s, but I want to do something a little different this time. I’m going to insert the HSBC Premier Mastercard as a point of comparison in each category, because I believe it can be an alternative to getting a S$120K card altogether.
To be clear, the HSBC Premier Mastercard is not a S$120K card, and is not eligible to win any of the category awards. In fact, the qualification requirement is rather different.
 |
 |
|
| S$120K cards | HSBC Premier Mastercard | |
| Min. Income | S$120K | S$30K |
| Min. AUM | Not required | S$200K |
| Annual Fee | S$498 to S$654 Generally not waivable |
S$708.50 Waived |
Instead of a S$120K income requirement, the HSBC Premier Mastercard only requires you to earn S$30K — though you will need a minimum AUM of S$200K. The annual fee of S$708.50 is waived so long as the minimum AUM is maintained.
Obviously, if you park the funds in a savings account that earns close to negligible interest, then the opportunity cost is effectively the “annual fee” of your HSBC Premier Mastercard. Fortunately, it doesn’t have to be that way. HSBC also includes equities, ETFs, index funds and money market funds in its calculations. It’s beyond the scope of my expertise to tell you how you should be allocating the S$200,000, suffice to say the higher the return you can generate, the better a deal the HSBC Premier Mastercard is.
What’s changed since last year?
Here’s a quick snapshot of what’s changed since the previous S$120K showdown in July 2025.
| AMEX Platinum Reserve |
|
| 👍 Improvements | 👎 Devaluations |
|
|
| Citi Prestige Card |
|
| 👍 Improvements | 👎 Devaluations |
|
|
 DBS Vantage Card |
|
| 👍 Improvements | 👎 Devaluations |
| Nothing I’m aware of! |
|
| Maybank Visa Infinite |
|
| 👍 Improvements | 👎 Devaluations |
|
|
| OCBC VOYAGE Card |
|
| 👍 Improvements | 👎 Devaluations |
| Nothing I’m aware of! |
|
| Standard Chartered Visa Infinite |
|
| 👍 Improvements | 👎 Devaluations |
|
|
| UOB Visa Infinite Metal Card |
|
| 👍 Improvements | 👎 Devaluations |
| Nothing I’m aware of! |
|
And now, the head-to-head!
Annual fees and welcome/renewal gifts
| Card | Annual Fee | Welcome / Renewal Gift |
| AMEX Platinum Reserve Apply |
S$545 | 1N stay at Fraser properties + dining & lifestyle vouchers Recurring |
| Citi Prestige Card 🥇 Winner 🥇 Apply |
S$651.82 | 32,000 miles Recurring |
| DBS Vantage Card Apply |
S$599.50 | 25,000 miles Recurring |
| Maybank Visa Infinite Apply |
S$654 (1st Year Free) |
None |
| OCBC VOYAGE Card Apply |
S$498 |
15,000 miles Recurring |
| SC Visa Infinite Apply |
S$599.50 | 25,000 miles First Year 20,000 miles Recurring |
| UOB Visa Infinite Metal Card Apply |
S$654 | 25,000 miles Recurring |
| 🏦 Premier Banking Alternative |
||
| HSBC Premier Mastercard Apply |
Waived | None |
If you want to join the S$120K club, you’d better get used to the idea of paying annual fees, and not insignificant ones— the annual fee for a S$120K card ranges from S$498 to S$654.
On the bright side, most S$120K cards cushion the blow by offering miles in exchange for the annual fee:
- The Citi Prestige, DBS Vantage, OCBC VOYAGE, and UOB Visa Infinite Metal Card offer bonus miles each year the annual fee is paid
- The Standard Chartered Visa Infinite offers 25,000 miles as a welcome gift, and 20,000 miles as a renewal gift in subsequent years
- The AMEX Platinum Reserve does not offer miles with the annual fee, but renewing members receive another 1N Fraser Hospitality voucher upon renewal, plus other dining and spa vouchers
- The Maybank Visa Infinite does not offer miles with the annual fee, but waives the first year’s fee
The Citi Prestige has the lowest-cost miles here: S$651.82 for 32,000 miles each year, or 2.04 cents each. 2.04 cents per mile may sound expensive, but remember: you’re not just buying miles with the annual fee. You’re getting other benefits like lounge access that need to be factored into the equation as well.
| 💸 Annual Fee Waiver? |
|
While S$120K cards generally don’t provide annual fee waivers, there are two exceptions:
The DBS Vantage used to offer an annual fee waiver with a minimum spend of S$60,000, but this ended in August 2026. |
Sign-up bonus
| Card | Min. Spend | Sign-Up Bonus |
| AMEX Platinum Reserve Apply |
N/A | N/A |
| Citi Prestige Card Apply |
S$14,000 | 45,000 miles Existing New |
| DBS Vantage Card Apply |
N/A | N/A |
| Maybank Visa Infinite Apply |
N/A | N/A |
| OCBC VOYAGE Card Apply |
N/A | N/A |
| SC Visa Infinite 🥇 Winner 🥇 Apply |
S$2,000 | 50,000 miles Existing New |
| UOB Visa Infinite Metal Card Apply |
S$4,000 | 40,000 miles Existing 60,000 miles New |
| 🏦 Premier Banking Alternative |
||
| HSBC Premier Mastercard Apply |
S$5,000 | 58,200 miles + S$200 Apple voucher Existing New |
While renewing certain S$120K cards may be a difficult decision, the first year of membership can be considerably more lucrative thanks to sign-up bonuses.
Unfortunately, this segment is going through kind of a rough patch right now. At the time of writing, sign-up bonuses are offered by the Citi Prestige, Standard Chartered Visa Infinite and UOB Visa Infinite Metal Card.
| ❓ Sign-up bonus vs welcome/renewal gift |
|
Sign-up bonuses are different from welcome/renewal gifts. Sign-up bonuses refer to bonus miles awarded for meeting a certain minimum spend within a certain period of approval. Welcome/renewal gifts are bonus miles awarded for simply paying the annual fee, without any spend necessary. |
When comparing sign-up bonuses, there are two things to consider:
- Is the bonus available to both new-to-bank and existing customers?
- What is the payoff ratio (bonus miles divided by minimum spend)?
Fortunately, all of the sign-up bonuses here are available to new-to-bank and existing customers — though the UOB Visa Infinite Metal Card offers a smaller bonus for the latter group.
This also means that you should not apply for a S$120K card as your first card for a given bank. Instead, apply for another card first (preferably one with a juicy SingSaver gift), then for the S$120K card as an existing customer.
In terms of payoff ratios, this year was brutal for the Citi Prestige Card, which in January 2026 increased its minimum spend sevenfold to S$14,000 while cutting the welcome bonus by 20% from 57,000 to 45,000 miles.
That means the payoff ratio nosedived from an excellent 28.5 to just 3.2. Sure, you can meet the minimum spend with Citi PayAll, but it’s a drastic reduction.
The UOB Visa Infinite Metal Card continues to offer something to both new and existing customers, but with a modest payoff ratio of 10 (existing) or 15 (new).
So I’m giving this title to the Standard Chartered Visa Infinite, which offers 50,000 miles for S$2,000 spend, a payoff ratio of 25. Because this offer is for existing customers too, you can actually apply for a different Standard Chartered card first, like the Journey Card (20,000 miles + S$180 cash), then apply for the Visa Infinite.
Earn rates
| Card | Local | FCY | Min. Spend for Points |
| AMEX Platinum Reserve Apply |
0.57 mpd | 0.57 mpd | S$1.60 |
| Citi Prestige Card Apply |
1.3 mpd^ | 2 mpd^ | S$1 |
| DBS Vantage Card Apply |
1.5 mpd | 2.2 mpd | S$1.34 (SGD) S$0.91 (FCY) |
| Maybank Visa Infinite Apply |
1.2 mpd | 3.2 mpd* | S$5 |
| OCBC VOYAGE Card Apply |
1.3 mpd |
2.2 mpd | S$5 |
| SC Visa Infinite 🥇 Winner 🥇 Apply |
1.4 mpd# | 3 mpd# | S$0.20 (SGD) S$0.10 (FCY) |
| UOB Visa Infinite Metal Card Apply |
1.4 mpd | 2.4 mpd | S$5 |
| ^Additional 0.02 to 0.12 mpd awarded based on tenure with bank *With minimum S$4K spend per calendar month. Otherwise 2 mpd #With minimum S$2K spend per statement month. Otherwise 1 mpd for both |
|||
| 🏦 Premier Banking Alternative |
|||
| HSBC Premier Mastercard Apply |
1.68 mpd | 2.76 mpd | S$0.16 (SGD) S$0.09 (FCY) |
For the record, you shouldn’t be spending regularly on your S$120K card in the first place, because every dollar put on a S$120K card is a dollar that isn’t earning 4 mpd on a specialised spending card.
But for argument’s sake, let’s suppose you do spend regularly on your S$120K card (maybe because you’ve burst the bonus caps on 4 mpd cards already).
In that case, the Standard Chartered Visa Infinite would be the best bet with its 1.4/3 mpd earn rates for local/overseas spend. However, you must spend at least S$2,000 per statement month, or else you’ll earn just 1 mpd for both. Also note that its 3.5% FCY transaction fee is slightly higher than the rest of the S$120K cards, which charge 3.25%.
If you don’t want to bother with minimum spends, the next best would be the UOB Visa Infinite Metal Card, which earns 1.4/2.4 mpd for local/overseas spend. But you will also need to deal with UOB’s annoying S$5 earning blocks, which result in lost miles due to rounding, especially if the typical transaction size on your S$120K card is less than S$50.
To avoid that, consider the DBS Vantage Card as an alternative. You can earn 1.5/2.2 mpd on local/overseas spend, with smaller earning blocks than UOB.
The Maybank Visa Infinite has so-so local spend rates, but if you’re spending big overseas, then its uncapped 3.2 mpd on FCY spend is the best in the segment — and with a 3.25% FCY fee, it’s cheaper than the Standard Chartered Visa Infinite too.
| 💳 OCBC Premier VOYAGE |
| It’s worth mentioning that if you qualify for an OCBC Premier VOYAGE (min. AUM: S$350,000), you’ll enjoy earn rates of 1.6/2.3 mpd for local/overseas spend. |
Points flexibility and expiry
| Card | Points Expiry | Transfer Partners (Fee) |
Min. Transfer* |
| AMEX Platinum Reserve 🥇 Winner 🥇 Apply |
None | 11 Free |
250 miles Pool |
| Citi Prestige Card Apply |
None | 11 S$27.25 |
10K miles |
| DBS Vantage Card Apply |
36-37 mo. | 4 S$27.25 |
10K miles Pool |
| Maybank Visa Infinite Apply |
None | 4 S$27.25 |
10K miles Pool |
| OCBC VOYAGE Card Apply |
None | 9 S$25 |
1 mile |
| SC Visa Infinite Apply |
None | 2 S$27.25 |
10K miles |
| UOB Visa Infinite Metal Card Apply |
24-27 mo. | 3 Free |
10K miles Pool |
| *Refers to KrisFlyer, min. blocks may be different for other frequent flyer programmes |
|||
| 🏦 Premier Banking Alternative |
|||
| HSBC Premier Mastercard Apply |
37 mo. | 20 Free |
10K miles Pool |
Quantity of points is one thing; quality is another. When assessing points quality, we look at:
Based on these criteria, the AMEX Platinum Reserve is the clear winner:
- Membership Rewards Points don’t expire
- The minimum conversion block is just 250 miles
- Points pool with other AMEX cards (not that the pooling opportunities are great anyway)
- 11 transfer partners
- No conversion fees
- Instant conversions to Singapore Airlines and Qantas Frequent Flyer
Mind you, this says nothing about how easy it is to earn points, but rather how useful those points are. As we saw earlier, the AMEX Platinum Reserve has pathetic earn rates, so you won’t be racking up Membership Rewards Points very quickly!
In runner-up position is the Citi Prestige, whose ThankYou points never expire and can be transferred to 11 airline and hotel partners. Additional points can be accumulated fairly easily via Citi PayAll, though it’s relatively pricey outside of promotions. The drawback here is that ThankYou points don’t pool, and you have to pay a S$27.25 conversion fee.
As for the rest, the UOB Visa Infinite Metal Card can help anchor a UOB card portfolio, since conversions are free and UNI$ pool. You can use it as a conduit to cash out UNI$ earned on other cards like the UOB Preferred Visa, UOB Lady’s Card and UOB Visa Signature for free. The main catch is the limited number of transfer partners, and the 24-27 month expiry period.
The OCBC VOYAGE offers nine transfer partners, but the conversion rates are poor. For example, conversions to British Airways Avios and Asia Miles entail a 10% and 25% haircut respectively compared to KrisFlyer, when other banks offer conversions to these programmes at the same ratio as KrisFlyer. However, if KrisFlyer is all you care about, then the minimum conversion block is just 1 mile, allowing you to surgically transfer just the right number of miles required.
Miles purchase facilities
| Card | Buy Miles From | Limit |
| AMEX Platinum Reserve Apply |
N/A | N/A |
| Citi Prestige Card 🥇 Winner 🥇 Apply |
1.46-2 cpm (Citi PayAll) |
Actual bill amount |
| DBS Vantage Card Apply |
1.67 cpm (Tax payment) |
Actual tax amount |
| Maybank Visa Infinite Apply |
N/A | N/A |
| OCBC VOYAGE Card Apply |
N/A | N/A |
| SC Visa Infinite Apply |
1.79 cpm (SC EasyBill) 1.36 cpm (SC Tax Payment Facility) |
Actual bill amount |
| UOB Visa Infinite Metal Card Apply |
1.8 cpm (UOB Payment Facility) |
No limit |
| 🏦 Premier Banking Alternative |
||
| HSBC Premier Mastercard Apply |
N/A | N/A |
A payment facility offers a way of earning miles on transactions which would normally not qualify, such as education, income taxes, rent or utility bills. A small fee is charged, so this is basically equivalent to buying miles.
To recap, there are two types of payment facilities:
- Those which let you buy as many miles as you want, no questions asked
- Those which let you buy miles provided you have a rental, tax, insurance or some other bill to pay
(1) is available to the UOB Visa Infinite Metal Card, with miles priced at a de facto rate of 1.8 cents each (the regular price is 2.2 cents, but there is an almost-perpetual promotion).
(2) is available to the Citi Prestige, DBS Vantage and Standard Chartered Visa Infinite, and the cost per mile can be significantly lower.
The lowest-cost option belongs to the Standard Chartered Visa Infinite, where you can pay income taxes with a 1.9% fee and earn up to 1.4 mpd, or 1.36 cents per mile. However, the cost for paying rent, education and insurance — handled through SC EasyBill — has now increased to 1.79 cents per mile, following a fee hike to 2.5%.
Because of the increased fee and the limited scope of payments, I’m giving this category to the Citi Prestige Card. During the 2026 income tax promotion, cardholders paid 1.46 cents per mile, and with the ongoing year-end promotion, cardholders are paying 1.77 cents per mile. The year-round price of 2 cents per mile is not as attractive, but PayAll spend also counts towards earning limo rides, which helps offset some of the cost.
Lounge access
| Card | Free Visits (Per Year) |
|
| Main | Supp. | |
| AMEX Platinum Reserve Apply |
N/A | N/A |
| Citi Prestige Card Apply |
12 CY Share |
N/A |
| DBS Vantage Card Apply |
10 MY Share |
N/A |
| Maybank Visa Infinite Apply |
4 | N/A |
| OCBC VOYAGE Card 🥇 Winner 🥇 Apply |
∞ No restaurants |
2 CY No Share^ |
| SC Visa Infinite Apply |
6 MY Share |
N/A |
| UOB Visa Infinite Metal Card Apply |
12 MY Share |
N/A |
| Legend | ||
| Whether visits are tracked by calendar year CY or membership year MY Whether lounge visits can or can’t be shared with guests Share No Share |
||
| ^While the T&Cs say that visits cannot be shared, cardholders report that sharing is possible | ||
| 🏦 Premier Banking Alternative |
||
| HSBC Premier Mastercard Apply |
∞ | ∞ (Max 3x supp. cards) |
Unlimited lounge access for S$120K cards is an endangered species, unfortunately.
The Maybank Visa Infinite got rid of unlimited visits in 2023, followed by the Citi Prestige in 2025 and the UOB Visa Infinite Metal Card in 2026.
That means the winner, purely by standing still, is the OCBC VOYAGE Card. Principal cardholders still enjoy unlimited DragonPass visits — for how long more is anyone’s guess — and supplementary cardholders receive two visits per year. The only fly in the ointment is that the DragonPass membership does not include restaurants.
Otherwise, 12 visits is the best you can hope for, offered by the Citi Prestige and UOB Visa Infinite Metal Card.
If unlimited lounge visits are something you really want, then you’ll have to look at the HSBC Premier Mastercard, or S$200K cards like the AMEX Platinum Charge and Standard Chartered Beyond Card.
Airport limo transfers
| Card | Qualifying Spend | Cap |
| AMEX Platinum Reserve Apply |
N/A | N/A |
| Citi Prestige Card Apply |
S$12K per quarter for 2 rides | 2 per quarter |
| DBS Vantage Card Apply |
N/A | N/A |
| Maybank Visa Infinite 🥇 Winner 🥇 Apply |
S$3K per month for 1 ride | 8 per year |
| OCBC VOYAGE Card Apply |
S$12K per quarter for 2 rides | 2 per quarter |
| SC Visa Infinite Apply |
N/A | N/A |
| UOB Visa Infinite Metal Card Apply |
N/A | N/A |
| 🏦 Premier Banking Alternative |
||
| HSBC Premier Mastercard Apply |
S$12K per quarter for 2 rides | 2 per quarter |
Only three S$120K cards offer an airport limo benefit.
The Maybank Visa Infinite is the clear winner, with the lowest minimum spend of S$3,000 per ride.
The Citi Prestige places second, with a minimum spend of S$12,000 per quarter for two rides. However, it does count transactions such as education, government services, hospital bills, insurance and utilities towards the minimum spend, as well as Citi PayAll, which makes it somewhat easier to obtain.
The OCBC VOYAGE places third. It has the same spending requirement as the Citi Prestige, but only rewards-earning transactions count as qualifying spend, and there’s no bill payment facility. What’s more, in November 2025, OCBC removed the ability to use limo rides for trips to bus and ferry terminals and land checkpoints.
Travel insurance
| Card | Coverage |
| AMEX Platinum Reserve |
|
| Citi Prestige Card 🥇 Winner 🥇 |
|
| DBS Vantage Card |
N/A |
| Maybank Visa Infinite |
|
| OCBC VOYAGE Card |
N/A |
| SC Visa Infinite |
|
| UOB Visa Infinite Metal Card |
|
| 🏦 Premier Banking Alternative |
|
| HSBC Premier Mastercard |
|
While most S$120K cards offer complimentary travel insurance, not all coverage is created equal.
In general, you’ll want to make sure your policy covers at least three things:
- Death and permanent disability: In case you perish or suffer permanent bodily damage while on your trip
- Medical expenses: In case you need to visit a doctor or a hospital overseas
- Travel inconvenience: Flight delays, lost and damaged luggage
If not, I’d highly advise you to buy a stand-alone insurance policy — preferably something that covers personal liability, loss of passport/personal money and rental car damage.
This is a close fight between the Citi Prestige and Standard Chartered Visa Infinite. I’d give the award to the former because it also covers situations where you booked your flights with miles and used the card to pay for taxes. However, I should highlight that this coverage is basically the generic World Elite Mastercard policy, as Citi scrapped its own policy back in February 2025.
Private club access
| Card | Private Club Access |
| AMEX Platinum Reserve 🥇 Winner 🥇 Apply |
Tower Club |
| Citi Prestige Card Apply |
N/A |
| DBS Vantage Card Apply |
N/A |
| Maybank Visa Infinite Apply |
N/A |
| OCBC VOYAGE Card Apply |
N/A |
| SC Visa Infinite Apply |
N/A |
| UOB Visa Infinite Metal Card Apply |
N/A |
| 🏦 Premier Banking Alternative |
|
| HSBC Premier Mastercard Apply |
N/A |
Not much of a contest here, really.
The AMEX Platinum Reserve continues to be the only S$120K card with private club access via Tower Club. Bookings can be made through the AMEX concierge, and access is limited to five cardholders per day. All expenses will incur a 10% surcharge, as is Tower Club’s policy for affiliate members.
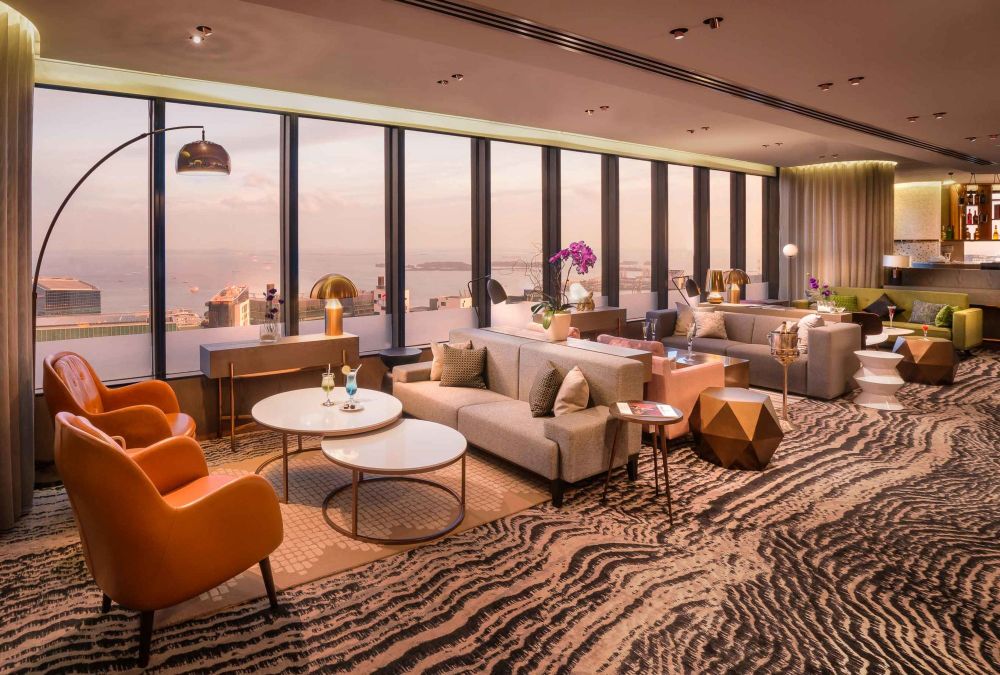
Although the Straits Bar is an okay place to have a drink (don’t expect anything other than paint-by-numbers cocktails though), I find the overall Tower Club experience a bit stuffy and overrated. It’s certainly not a decisive factor for choosing a S$120K card.
Dining perks
| Card | Dining Perks |
| AMEX Platinum Reserve 🥇 Winner 🥇 Apply |
|
| Citi Prestige Card Apply |
|
| DBS Vantage Card Apply |
|
| Maybank Visa Infinite Apply |
|
| OCBC VOYAGE Card Apply |
|
| SC Visa Infinite Apply |
|
| UOB Visa Infinite Metal Card Apply |
|
| 🏦 Premier Banking Alternative |
|
| HSBC Premier Mastercard Apply |
|
My take is that the AMEX Platinum Reserve offers the best all-round dining proposition.
Cardholders enjoy up to 50% off food with Love Dining at a wide range of hotels and restaurants around Singapore, including heavyweights like The Capitol Kempinski, St. Regis Singapore, W Singapore and Swissotel. There’s also Chillax, which gives 1-for-1 drinks at selected bars islandwide.
However, it’s worth noting that the exact same benefits can be enjoyed with an AMEX Platinum Credit Card, which has a lower annual fee of S$327.
The DBS Vantage is now worse off because of the October 2025 transition to ALL Accor+ Explorer, which saw the maximum dining discount slashed from 50% to 30% (see below). For what it’s worth, the discounts are valid across Asia Pacific, while AMEX’s discounts are for Singapore only.
The Citi Prestige and OCBC VOYAGE offer curated 1-for-1 dining experiences, but these are almost like lucky draws, because you have to act with superhuman speed to book a slot once they’re released.
Elsewhere, the UOB Visa Infinite Metal Card’s star is rapidly fading. Infinite Dining experiences have all but dried up, and its discounts with the Pan Pacific Hotels Group and Fullerton Hotels, which were once as high as 50%, are now in the 15-20% range.
Honourable mention goes to the Maybank Visa Infinite, which now benefits from Taste Circle discounts of up to 50% off. Taste Circle is available to all Maybank cardholders, but as a premium card, the Maybank Visa Infinite enjoys additional benefits such as 1-for-1 beverages, plus discounts at The Ritz-Carlton Millenia Singapore, Conrad Singapore Orchard and W Sentosa Cove.
Weight
What’s the point of having a S$120K card if you can’t let the whole world know by dropping it casually on the counter with a fragile-masculinity-assuaging “plunk”? (fun fact: the plunk factor is an actual term in the card manufacturing industry, describing the heft of a card).
That is, if your card is actually made of metal like the DBS Vantage, Citi Prestige, OCBC VOYAGE and UOB Visa Infinite Metal Card. The judging criteria here is simple: OCBC VOYAGE wins because it weighs the most.
| Card | Weight |
| AMEX Platinum Reserve Apply |
~5g |
| Citi Prestige Card Apply |
8g |
| DBS Vantage Card Apply |
10g |
| Maybank Visa Infinite Apply |
~5g |
| OCBC VOYAGE Card 🥇 Winner 🥇 Apply |
15g |
| SC Visa Infinite Apply |
~5g |
| UOB Visa Infinite Metal Card Apply |
9g |
Supplementary cardholder benefits
| Card | Supp. Cards | Perks |
| AMEX Platinum Reserve Apply |
2 free (3rd+ card: S$163.50) |
|
| Citi Prestige Card Apply |
Free |
|
| DBS Vantage Card Apply |
Free |
|
| Maybank Visa Infinite Apply |
Free |
|
| OCBC VOYAGE Card Apply |
S$191 (First year fee waived for first 2 supp. cards) |
|
| SC Visa Infinite Apply |
4 free |
|
| UOB Visa Infinite Metal Card Apply |
1 free (2nd+ card: S$293.38) |
|
| 🏦 Premier Banking Alternative |
||
| HSBC Premier Mastercard Apply |
3 free |
|
With some limited exceptions, the best perks are usually reserved for principal cardholders only. Indeed, with most S$120K cards, the best you can hope for are generic Visa Infinite or World Elite Mastercard benefits.
Here’s where Visa has closed the gap on Mastercard significantly over the past year, with its new suite of offers for Visa Infinite cardmembers including a complimentary New York Times subscription and Trip.com Diamond status.
 |
|
| 💳 World Elite Mastercard Benefits | |
| 🏨 Hotel Elite Status |
|
| 🚗 Rental Car Elite Status | |
| 👍Other Perks | |
 |
|
| 💳 Visa Infinite Benefits | |
| 🏨 Hotel Elite Status | |
| 🚗 Rental Car Elite Status | |
| 👍Other Perks |
|
The AMEX Platinum Reserve offers supplementary cardholders the same Love Dining, Chillax and Tower Club access perks that the principal cardholder enjoys. But again, you could get the same benefits (except for Tower Club access) with the cheaper AMEX Platinum Credit Card, so this alone shouldn’t be a reason to get the AMEX Platinum Reserve.
The OCBC VOYAGE Card offers two lounge visits for supplementary cardholders, but that’s still nothing compared to the unlimited visits they received prior to March 2024.
The Standard Chartered Visa Infinite Card allows supplementary cardholders to use its income tax payment facility and buy miles from 1.36 cents each, which may be useful if they have tax bills of their own to pay.
This is a really tough one. I don’t want to be forced to call a winner when there’s nothing really outstanding, so I won’t.
Unique perks
In addition to the benefits above, some S$120K cards have unique perks which are worth discussing.
Citi Prestige: 4th Night Free
One of the biggest draws of the Citi Prestige Card is the 4th Night Free benefit, which allows principal cardholders to stay four nights at a hotel for the cost of three.
- The principal cardholder must make a reservation in their own name for a stay of a minimum of four consecutive nights
- The reservation must be made through the Citi Prestige Concierge or Citi Prestige Digital Concierge
- The reservation must be fully prepaid at the time of booking
- The rate must be available on the hotel’s public website, or via Expedia
If the above criteria are satisfied, the average pre-tax rate of the first four nights will be refunded within two billing cycles (up to 90 days) from completion of full payment.
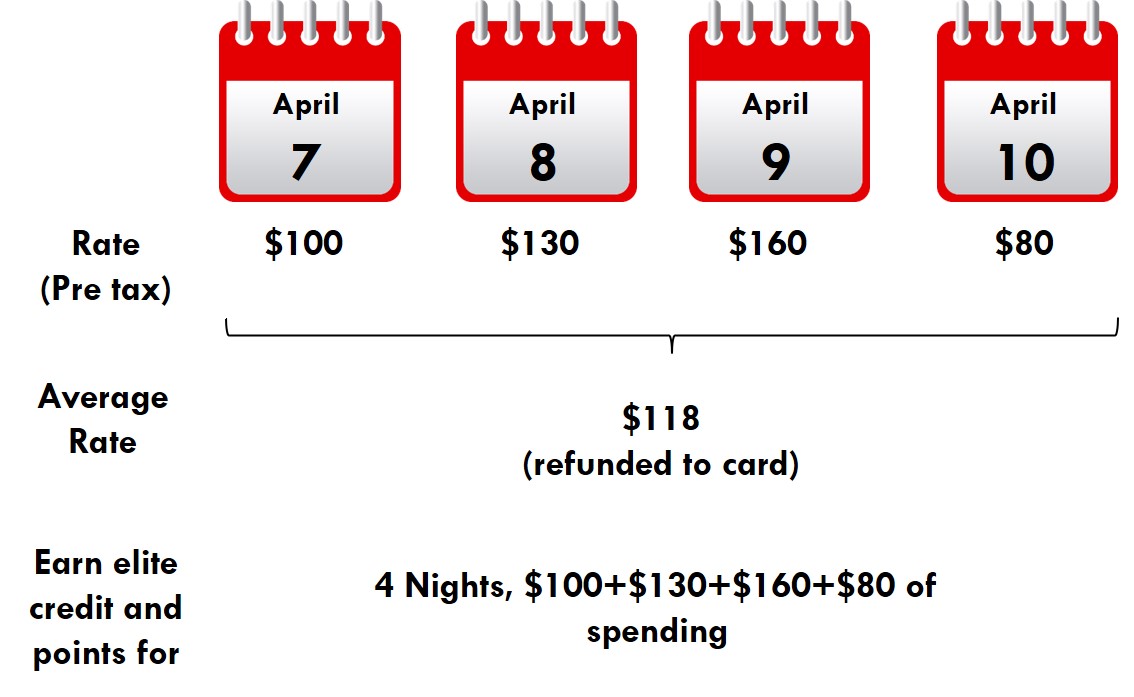
In the example above, the cardholder receives a refund of S$118 (the average of S$100, S$130, S$160 and S$80). Since the refund is on the Citi side, elite credit and hotel points (if applicable) are earned on the full amount of spending.
A maximum of one free night can be enjoyed per stay, and back-to-back stays will not be honoured. Back-to-back stays are defined as consecutive stays:
- In the same hotel, same city
- In a different hotel, in the same city
Consecutive stays are defined as any stay in which the check-in date is less than seven days from the previous check-out date.
The 4th Night Free benefit does not apply to:
- Full and half board room stays
- Single and multi-room suites
- Home & farm stays
- Serviced apartments
- Villas
- Packaged stay and member rates, such as air and hotel, hotel and car rental, hotel and meals bundled promotions
Moreover, the 4th Night Free benefit won’t really save you 25%, because:
- OTAs may be offering lower rates, which allow you to stack promo codes, 4 mpd cards or even bonus miles from bank x OTA portals
- You can’t stack it with ShopBack cashback or HeyMax Max Miles
- You cannot book member rates, even if the membership is free to join
- The free night doesn’t include taxes
So can this benefit justify the annual fee? It all boils down to how you use it. There is no cap on the number of times you can use it each year, nor the maximum rebate you can receive. This benefit could be worth nothing at all, or it could single-handedly cover your annual fee.
DBS Vantage: ALL Accor+ Explorer membership

The big change for the DBS Vantage Card is that the Accor Plus Explorer membership has now become ALL Accor+ Explorer, effective 1 October 2025.
Whether this was an enhancement or a devaluation depends on your perspective, but what is clear is that the maximum dining discount has been reduced to 30%, and the Stay Plus free night benefit now requires a minimum of one paid night.
 |
 |
|
| Accor Plus | ALL Accor+ Explorer | |
| Price (in Singapore) |
S$418 (1 free night) S$538 (2 free nights) |
S$299 (2 free nights) |
| Stay Plus | No paid night required | At least one paid night required |
| Dining Discount | Up to 50% off | Up to 30% off |
| Drinks Discount | 15% off (Asia only) |
15% off (Asia Pacific) |
| Status Nights | 20 | 30 |
| Status Renewal* | Yes | No |
| Hotel Discount | 10% off (lowest rate, Asia Pacific) |
15% off (best flexible rate, worldwide) |
| *When purchasing or renewing Accor Plus, status was assessed using the higher of year-to-date or previous year activity, allowing members to extend status based on last year’s activity. With ALL Accor+ Explorer, status is reviewed strictly at year-end, removing this possibility | ||
Moreover, the cost of a membership dropped from S$418 to S$299 (becoming S$329 on 1 October 2026), which will affect how you value the DBS Vantage Card.
OCBC VOYAGE: Redeem miles for any flight
A unique feature of OCBC VOYAGE is that VOYAGE Miles can be used to pay for any flight in any cabin on any airline. It’s conceptually the same as buying a commercial ticket, freeing you from the uncertainties of award inventory and waitlisting, and presenting the opportunity to earn miles and elite status credits on your flight.
The value of a VOYAGE Mile when redeemed for commercial airfares is opaque, but prior to August 2023, it was reliably around 2.3 cents. Unfortunately, OCBC then carried out an unannounced 25% devaluation, which reduced the value to no more than 1.72 cents.
But that’s just the risk you bear when holding VOYAGE Miles. Since there’s no official value per mile, the value is whatever OCBC says it is!
Category Recap
Before we unveil the overall winner, let’s first recap the results of each category (and keep in mind that I wouldn’t weigh each category the same):
| 🥊 S$120K Credit Card Showdown 🥊 | |
| Category | Winner |
| Annual Fees & Welcome/Renewal Gift | Citi Prestige Card |
| Sign-up Bonus | SC Visa Infinite |
| Earn Rates | SC Visa Infinite |
| Points Flexibility & Expiry | AMEX Platinum Reserve |
| Miles Purchase Facility | Citi Prestige Card |
| Lounge Access | OCBC VOYAGE Card |
| Airport Limo | Maybank Visa Infinite |
| Travel Insurance | Citi Prestige Card |
| Private Club Access | AMEX Platinum Reserve |
| Dining Perks | AMEX Platinum Reserve |
| Weight | OCBC VOYAGE Card |
| Supp. Cardholder Benefits | No winner |
🏆 Winner: Citi Prestige Card
Over the past nine years of writing this post, one thing has become increasingly clear: S$120K cards aren’t what they used to be.
Banks have long viewed S$120K cards as loss leaders, using them to onboard affluent customers before cross-selling higher-margin insurance and investment products. Evidently, this strategy hasn’t worked out to the extent they had hoped, and rising costs for airport limo rides and lounge access have made it increasingly difficult to sustain the value proposition.
Therefore, banks have been forced to cut benefits or increase annual fees — or both, in the case of the Citi Prestige. They’re also reformulating their premium cards strategy by:
- Tying benefits to AUM, as with the HSBC Premier Mastercard
- Creating a new “super premium” segment with four-digit fees, like the Standard Chartered Beyond Card
So where does that leave the S$120K segment? Well, if you have a pre-COVID picture of a S$120K card, with unlimited lounge access, airport limo rides with reasonable minimum spends, and solid travel insurance, then the closest thing to that is the HSBC Visa Infinite — only that ship has sailed. If you’re one of the old-timers with this card, treasure it while you can!
Otherwise, the OCBC VOYAGE remains the only S$120K card to offer unlimited lounge visits, and at S$498, is the cheapest option too. But the only reason it’s attractive is because other cards have gotten worse, not because it’s gotten better. That’s not really a ringing endorsement.
So apologies if I sound like a broken record here, but the Citi Prestige still offers the best path to annual fee recovery, because for S$651.82, you get:
- 12 lounge visits
- 32,000 miles
- 4th Night Free benefit
There are other ways of getting value too — if you golf, if you’re lucky enough to grab the 1-for-1 Haute Dining, if you use the Citi PayAll promotions to earn limo rides (a S$12,000 tax bill with April 2026’s promotion would earn two rides, a S$80 eCapitaVoucher and 15,600 miles for S$228). Furthermore, the recent discounts on Singapore Airlines fares — up to S$120 per ticket — could be as good as cash if you were planning to book those flights anyway.
All in all, there should be enough here to cover the annual fee, especially if you use the 4th Night Free benefit at least twice a year.
Conclusion
If there’s one takeaway from this year’s showdown, it’s that the case for owning a S$120K card gets more and more marginal each year. You can definitely come out ahead, but the amount of effort required continues to grow — which I have to believe is a deliberate decision.
As for me, I’ve already shifted away from this segment. The way I see it, the HSBC Premier Mastercard is a superior alternative, provided you can earn a decent enough return on your AUM with HSBC. And if you really want the kind of exclusive experiences that S$120K cards offered once upon a time, you probably have to start looking at the segment above it, whether S$200K or even S$500K. Like it or not, S$120K ain’t what it used to be.
Remember: no one needs a S$120K card to play the miles game. If your goal is simply to accumulate miles as quickly as possible, you’d be better off with the cards I recommend in my annual card strategy post, most of which are available with an annual income of just S$30,000.
Which S$120K card do you like the most?
