
As we speed through the last quarter of 2026, it’s time to update The MileLion’s 2026 Credit Card Strategy, my blueprint for earning miles on a day-to-day basis.
A lot has happened since my last update in May 2026, but don’t worry if you haven’t been keeping up — I’ll get you up to speed on the latest, then share how it’s changed my overall card strategy.
| 💳 2026 Credit Card Strategy |
| Abbreviations: c. month = calendar month, s. month = statement month, m. year = membership year |
What’s changed since the last edition?
Here’s a summary of the key updates since I last published this guide in May 2026.
- Whisper it quietly, but HealthHub transactions might now be coding as MCC 8062 (#1, 2, 3), though other recent data points (#1, 2) also have it as MCC 9399 so proceed with caution. If it’s 8062, you can use the Trust Freedom Card for 1.3 mpd
- yuu Points to Max Miles conversions are finally available, turning the DBS yuu Card into a “Max Miles card”
- The new Trust Freedom Card now offers a “free miles” option on overseas spend, with 1.3 mpd and no FCY transaction fees
- CardUp had a major hike in payment processing fees, which places the cost per mile into unattractive territory — unless you use PayNow
- SC EasyBill quietly increased its admin fee to 2.5%, without notice
- The GXS Credit Card launched with 10% rebates on overseas Grab spend
- The Chocolate Visa Card received a buff to its caps, with 1 mpd on up to S$2,000 per month and 300 miles per month on bill payments
- HSBC Premier Mastercard now earns miles on overseas education
- UOB PRVI Miles added a 5,000 miles quarterly spending bonus, but also increased the minimum spend for its loyalty bonus to S$80,000
- HeyMax First has added an almost-too-good-to-be-true opportunity to generate credit card miles from just 0.36 cents each
- A small, obscure debit card called the EZ-Link Mastercard disappeared silently into the night…
I keep tabs on all the nerfs and buffs on this calendar, so be sure to bookmark it.
Important reminders
Before we talk about specific cards, here are a few important points to make.
Not a comprehensive listing
First, this article is not intended to be a comprehensive listing of the best cards for each category. There are other cards that could work just as well, so please don’t flood the comments with “why not Card X for category Y?”
Remember, the idea here is to present a strategy rather than a compendium. If you’re interested in a comprehensive listing of the best cards for a given category, you should instead refer to the articles below.
Don’t forget sign-up bonuses
Second, this article doesn’t take into account ongoing sign-up bonuses.
These are opportunities for new cardholders to earn a lump sum of miles by spending a minimum amount within a certain period following approval. You should absolutely try to take advantage of these first, because the effective earn rate (in terms of miles awarded per dollar spent) will be superior to many of the cards in this post.
I publish a monthly article that covers all the sign-up bonuses in detail, and you can also bookmark my Welcome Offers page to keep tabs on the latest promotions.
Categories can overlap
Third, categories can overlap or be subsets of each other, so don’t think about them too rigidly.
For example, a card which earns bonuses on contactless payments can be used at a restaurant, department store, supermarket, or anywhere that contactless payments are accepted. Likewise, if a card earns bonuses on foreign currency spend, it doesn’t matter whether that spend is dining, shopping or travel-related.
Check the definitions
Fourth, different cards may define the same category differently. What counts as dining for HSBC may be different from UOB!
Always refer to the T&Cs for the exact list of eligible MCCs, and if you need to check the MCC of a given merchant, use the methods below.
| Method | Ease of Use | Reliability |
| ❓HeyMax | ●●● | ● |
| 💳 Trust Card | ●● | ●● |
| 📱 Instarem App | ●● Up to 15-min delay |
●● |
| 🤖 DBS digibot | ● |
●●● |
Calendar month versus statement month
Your card’s bonus cap may be based on the calendar month or statement month.
- Calendar month is straightforward (e.g. 1-31 January)
- Statement month varies from person to person. You can check it by looking at the statement date on your eStatement. This is the last day of the statement month. For example, if the last day of the statement month is the 12th, the statement month runs from the 13th of this month to the 12th of the following month
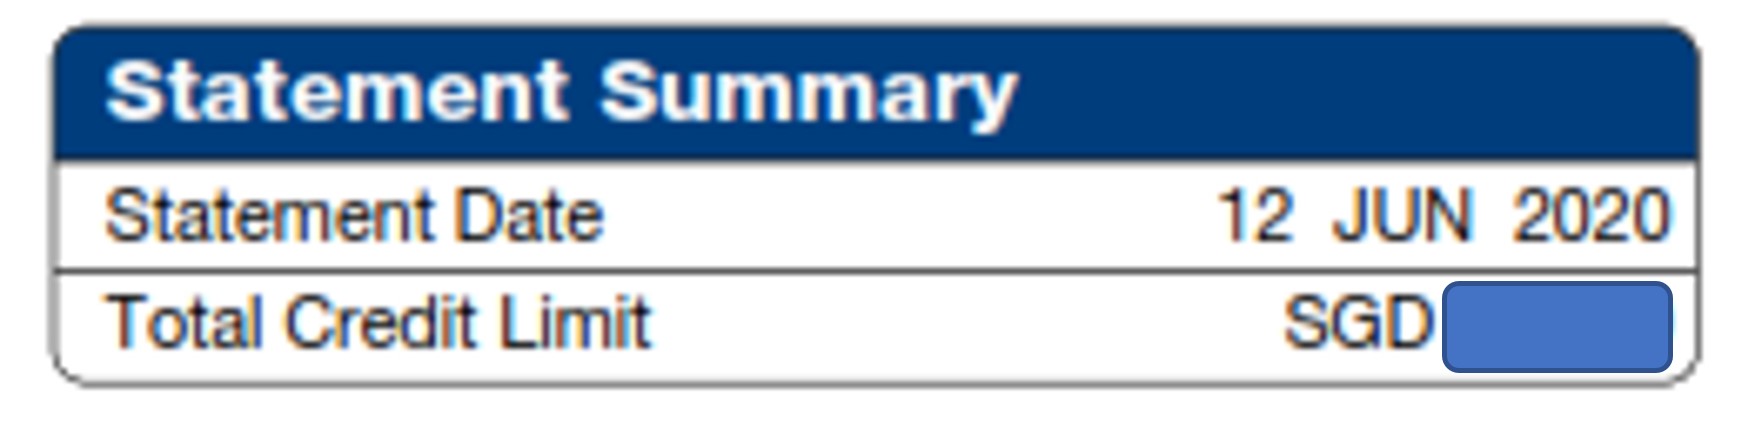
It may be possible to call up the bank and request for your statement month to be shifted to a date that more closely aligns with the calendar month. That’s what I’ve done with my UOB Visa Signature, and now its statement date matches the calendar month (disclaimer: banks have a certain quota per date, so it might not be possible to shift yours).
What cards am I using for 2026?
Here’s a quick summary of the cards that I’ll be using the most in 2026.
| Card | Categories |
 Citi Rewards Card Apply |
4 mpd |
 DBS Woman’s World Card Apply |
4 mpd |
 DBS yuu AMEX/Visa AMEX Visa |
10 mpd |
 HSBC Revolution Apply |
4 mpd |
 KrisFlyer UOB Credit Card Apply |
3 mpd |
 Maybank Horizon Visa Signature Apply |
2.8 mpd |
 Maybank World Mastercard Apply |
3.2 mpd
4 mpd |
 Maybank XL Rewards Apply |
4 mpd |
 OCBC Rewards Card Apply |
6 mpd |
 UOB Lady’s Solitaire Dining Fashion Apply |
4 mpd |
 UOB Preferred Visa Apply |
4 mpd |
 UOB Visa Signature Apply |
4 mpd |
| 👍 Extra miles for banking accounts |
|
The UOB Lady’s Cards and HSBC Revolution Card offer bonus miles to cardholders who maintain a certain minimum balance in a UOB Lady’s Savings Account and HSBC Everyday Global Account each month.
It’s beyond the scope of this article to discuss whether the bonus miles are worth the opportunity cost of those funds, but you can find a more detailed analysis in the links above. |
I realise that one dozen cards may seem like a lot to keep track of, but once you learn the general heuristics, it’s really not as complicated as it seems (honest!).
Also, if your monthly spending is more modest, it’s highly unlikely you’ll need all the cards shown above. Those spending less than S$3,800 per month could use the following “minipack” to earn 4 mpd on almost everything, without the need to memorise specific categories.
| 💳 “Minipack” For Smaller Spenders |
||
| Card | Monthly Spend | Remarks |
| Citi Rewards Apply |
S$1,000 S. Month |
Online transactions (except travel and in-app mobile wallet) |
| DBS Woman’s World Card Apply |
S$1,000 C. Month |
Online spend |
| UOB Preferred Visa Apply |
S$600* C. Month |
Mobile contactless |
| UOB Visa Signature Apply |
S$1,200^ S. Month |
Contactless spend (min. S$1,000 per s. month) |
| *Additional S$600 monthly bonus cap for selected online transactions including dining, groceries, entertainment and shopping ^Additional S$1,200 monthly bonus cap for FCY transactions, with min. spend S$1,000 per s. month |
||
You will miss out on some higher-earning opportunities — like 6 mpd with the OCBC Rewards or 10 mpd with the DBS yuu Card — but this keeps things extremely straightforward.
What card for which category?
Contactless Payments
| Card | Earn Rate | Remarks |
| UOB Preferred Visa Apply |
4 mpd | Max S$600 per c. month Review |
| UOB Visa Signature Apply |
4 mpd | Min S$1K, max S$1.2K per s. month in SGD Review |
A bonus for contactless payments is practically a licence to earn 4 mpd everywhere, given how ubiquitous contactless terminals are nowadays.
| ❓Well, not everywhere |
| I shouldn’t have to say this (though based on some angry emails I receive, perhaps I do), but UOB’s standard exclusion list still applies. You won’t earn 4 mpd if you use contactless payments at an educational institution or government office, for instance. |
Nothing changes here. The UOB Preferred Visa continues to be the go-to option, with 4 mpd on all mobile contactless transactions. Simply add it to your Apple, Google or Samsung Pay account and tap your phone or watch in-store to pay.
The unfortunate thing is that the bonus cap for mobile contactless is just S$600 per calendar month. If you want to continue getting the most out of this card, you must utilise its lesser-known bonus category: 4 mpd for online food delivery, groceries, entertainment and shopping (hint: buying HeyMax vouchers is an easy way of maxing this out).
If you need more bonus cap, then the UOB Visa Signature offers 4 mpd on all contactless transactions of up to S$1,200 per statement month, with a minimum spend of S$1,000.
Do note that each card defines contactless spending slightly differently. You will not earn any bonuses if you tap the physical UOB Preferred Visa card!
|
|
|
| UOB PV | UOB VS | |
 |
✅ | ✅ |
 |
❌ | ❌ |
 |
✅ | ✅ |
 Excludes MST |
✅ | ✅ |
 Tapping physical card |
❌ | ✅ |
| ❓ What about in-app or online payments? |
|
In-app or online payments are not considered contactless payments. However, they may earn bonuses on the UOB Preferred Visa if the MCC matches the online bonus whitelist. Contactless payments in this context refer to in-store transactions only. Simple rule: if you hear a beep when you pay, it’s contactless. |
Since the bonus caps for contactless spending are fairly tight, it’s important to be familiar with ways of turning offline spend into online, in case you need to spend in-store and have busted the caps already.
Online Transactions
| Card | Earn Rate | Remarks |
| Citi Rewards Apply |
4 mpd | Excludes travel and in-app mobile wallet. Max S$1K per s. month Review |
| DBS Woman’s World Card Apply |
4 mpd | Max S$1K per c. month Review |
Like contactless payments, online transactions are another big catch-all category.
Both the Citi Rewards and DBS Woman’s World Card earn 4 mpd on online transactions, so long as it doesn’t fall into:
- the bank’s general list of exclusions, or
- in the case of the Citi Rewards
- travel-related transactions such as airlines, cruises, hotels, rental cars and travel agencies
- in-app mobile wallet payments (e.g. FoodPanda + Citi Rewards = 4 mpd, FoodPanda + Google Pay (using Citi Rewards) = 0.4 mpd)
| ❓ Blacklist vs Whitelist |
|
The HSBC Revolution, Maybank XL Rewards or UOB Preferred Visa can also earn 4 mpd for certain online transactions, but exercise caution because these cards follow a “whitelist” approach: a given online transaction doesn’t earn 4 mpd unless its MCC falls within the inclusion list. Contrast this with the Citi Rewards and DBS Woman’s World Card, which follow a “blacklist” approach: a given online transaction will earn 4 mpd unless its MCC falls within the exclusion list. If the whole concept of whitelist and blacklist confuses you, refer to this post. |
In other words, both the Citi Rewards and DBS Woman’s World Card would be well-suited to cover everyday transactions like:
- Food delivery
- Ride-hailing
- Movie tickets
- Google Play or Apple App Store purchases
- Netflix, Spotify and other streaming subscriptions
- E-commerce sites like Amazon, Lazada, Shopee etc.
- (WWMC only) Buying airline tickets, cruises, prepaid hotels or activities & attraction bookings with Klook or Pelago
If I had to choose between the two, I’d lean in the direction of the Citi Rewards Card, simply because its points have a longer validity (up to 5 years, versus 12-15 months for the WWMC) and more transfer partners (11, versus 4 for the WWMC). However, it does have an annoying exclusion for travel, so that’s something to consider too.
For spending specifically on Shopee, Lazada, Taobao or TikTok Shop, however, I’d bring in the OCBC Rewards Card to take advantage of its 6 mpd promo, available till 31 March 2027. This is capped at S$1,000 per calendar month.
HeyMax
| Card | Earn Rate | Remarks |
| UOB Lady’s Solitaire Apply |
4 mpd | Max S$750 per c. month, with Fashion as bonus category Review |
| UOB Preferred Visa Apply |
4 mpd | Max S$600 per c. month Review |
HeyMax, better known for its MCC lookup tool, also sells vouchers for numerous merchants, and all purchases will code as MCC 5311 Department Stores.
 |
|
| Get 200 Max Miles when you sign up for a HeyMax account and complete one transaction | |
| Sign up here |
|
|
|
Therefore, whether you’re buying electronics or furniture, booking activities, taking a Grab or ordering food delivery, buying eSIMs or shopping online, you can use HeyMax to change the MCC to 5311.
Buying HeyMax vouchers also helps manage the annoying S$600/S$750 bonus sub-caps on the UOB Preferred Visa/UOB Lady’s Solitaire (I’ve switched one of my bonus categories to Fashion, which covers 5311), because it’s much easier to buy vouchers in exact denominations to hit the caps, rather than spending “in the wild”.
Of course, you could just as well use the HSBC Revolution, Maybank XL Rewards or OCBC Rewards here too, but in my case, those bonus caps are usually tied up elsewhere.
Atome
| Card | Earn Rate | Remarks |
| Citi Rewards Apply |
4 mpd | Max S$1K per s. month Review |
| DBS Woman’s World Card Apply |
4 mpd | Max S$1K per c. month Review |
| HSBC Revolution Apply |
4 mpd | Max S$1K per c. month Review |
Atome may have its detractors, but I think it’s a great tool for any miles chaser. With Atome, you can:
- Break up transactions into three interest-free monthly payments, stretching your cashflow and better optimising the monthly bonus caps on specialised spending cards
- Enjoy extra discounts at selected merchants
- Convert non-bonused MCCs into bonus-earning MCCs
- Convert ineligible MCCs into reward-earning MCCs (Atome partners with quite a few educational institutions)
- Double dip on credit card miles and Atome+ Points (which can be converted into KrisFlyer miles and Max Miles)
Do remember to trigger payments manually a few days before they’re due, as automated recurring payments may not be eligible to earn miles.
Atome counts as online spend, so you can use both the Citi Rewards Card and DBS Woman’s World Card, in addition to the HSBC Revolution Card. Since I prefer to save the first two for spending elsewhere, the HSBC Revolution usually handles this category.
Dining
| Card | Earn Rate | Remarks |
 DBS yuu AMEX Apply |
10 mpd |
FoodPanda only. Min. spend of S$800 & cap of S$823 per c. month. Must spend at 4x participating merchants |
 DBS yuu Visa Apply |
10 mpd | |
| HSBC Revolution Apply |
4 mpd | Max S$1K per c. month Review |
| Maybank XL Rewards Apply |
4 mpd | Min. S$500, max S$1K per c. month Review |
| UOB Lady’s Solitaire Apply |
4 mpd | Max S$750 per c. month, with Dining as bonus category Review |
The dining category includes both dining at restaurants and ordering through food delivery platforms like Deliveroo, GrabFood and FoodPanda (for which the 10 mpd DBS yuu Card should be the only choice).
Dining is the other bonus category on my UOB Lady’s Solitaire Card. However, this can also be covered by the HSBC Revolution, along with the Maybank XL Rewards Card.
Just be careful about how dining is defined, as the HSBC Revolution excludes MCC 5814 (Fast Food). Even if you don’t care for McDonald’s, Burger King or other junk food, 5814 can pop up in unexpected places because Visa and Mastercard have historically offered preferential rates for this MCC.
That created an incentive for restaurants to push for this classification, even if what they’re offering is the furthest thing from fast food. MCC 5814 has been reported at Shin Katsu, PS Cafe, Beyond the Dough, Tipo Pasta, MODU High, Sushisamba, Cafe Nesuto, and bakeries like Noci Bakehouse and Paris Baguette. It’s also used by GrabFood in Singapore.
Another MCC to be careful of is MCC 5499, which is used by Bengawan Solo (certain outlets), Nespresso, Cheers, 7-Eleven, Farm Frozen, and GrabFood in Malaysia. This MCC is excluded by the HSBC Revolution and Maybank XL Rewards.
| 🍽️ Dining MCC Coverage |
||||||
|
|
|
 |
 |
|
|
| MCC | UOB PV Online |
Revo | XL | Journey Online |
Lady’s Dining |
KF UOB |
| 5811 | ✅ | ✅ | ✅ | ✅ | ✅ | ❌ |
| 5812 | ✅ | ✅ | ✅ | ✅ | ✅ | ✅ |
| 5813 | ❌ | ✅ | ✅ | ❌ | ❌* | ✅ |
| 5814 | ✅ | ❌ | ✅ | ✅ | ✅ | ✅ |
| 5441 | ✅ | ✅ | ❌ | ❌ | ❌ | ❌ |
| 5462 | ✅ | ✅ | ✅ | ✅ | ❌ | ❌ |
| 5499 | ✅ | ❌ | ❌ | ✅ | ✅ | ❌ |
| *MCC 5813 is covered under the Entertainment category |
||||||
Foreign Currency (FCY) Spend
| Card | Earn Rate | Remarks |
 Amaze + Citi Rewards Apply |
4 mpd | Max S$1K per s. month Review |
| Maybank XL Rewards Apply |
4 mpd | Min. S$500, max S$1K per c. month Review |
| UOB Visa Signature Apply |
4 mpd | Min. S$1K, max S$1.2K per s. month on FCY spend Review |
| Maybank World Mastercard Apply |
3.2 mpd | Min. S$4K per c. month. 2.8 mpd with min. S$800 per c. month. No cap Review |
 Trust Freedom Card Apply via app with referral code 2GQEAM81 |
1.3 mpd | No cap Review |
This is the category that’s seen the most disruption, with the launch of the Trust Freedom Card.
We’ll get to that in a bit, but my first choice continues to be pairing the Citi Rewards Card with Amaze to earn 4 mpd on overseas spending with a ~2% FCY fee.
Otherwise, I’ll use the Maybank XL Rewards Card, which also earns 4 mpd provided the minimum spend of S$500 is met (you can also pair it with Amaze, though this should only be for whitelisted categories like dining, shopping, travel and entertainment).
Next in line is the UOB Visa Signature, though unfortunately the “sweet spot” for spending is now much narrower, following the introduction of bonus sub-caps. You used to be able to spend between S$1,000 and S$2,000, but now the target range is between S$1,000 and S$1,200, which leaves less room for error.
But what happens when the 4 mpd opportunities are exhausted?
Normally, I’d switch to the Maybank World Mastercard for an uncapped 3.2 mpd on FCY spend, but this requires a hefty minimum spend of S$4,000 per month.
Moreover, with the Trust Freedom Card offering 1.3 mpd and no FCY fee, the cost per mile with the Maybank World Mastercard is actually 1.62 cents per mile [3.25% ÷ (3.2 mpd x (1 + 3.25%) – 1.3 mpd)].
The math is marginal — it’s cheaper than the “ceiling price” set by the UOB Payment Facility of 1.8 cents per mile, but it’s still high enough to make me think twice. For some people, paying 1.62 cents each for an accelerated 3.2 mpd might be better than earning free miles at 1.3 mpd — especially if you’re getting reimbursed for your spending. If your miles balance is already healthy, you may feel otherwise.
What should be clear is that any overseas spending option earning 2.8 mpd or less should be off the menu for now, since that would push the cost per mile to 2.04 cents each or more.
Groceries
| Card | Earn Rate | Remarks |
| DBS yuu AMEX Apply |
10 mpd | Giant and Cold Storage only. Min. spend of S$800 & cap of S$823 per c. month. Must spend at 4x participating merchants Review |
| DBS yuu Visa Apply |
10 mpd |
The DBS yuu Card is the only logical option for grocery spending at Giant or Cold Storage, with its unbeatable 10 mpd (shopping at both also helps rack up two unique merchants towards the four merchant minimum).
For the occasions when I visit NTUC, or buy groceries on RedMart, I simply resort to cards which award bonuses for contactless payments (i.e. UOB Preferred Visa or UOB Visa Signature) or online transactions (i.e. Citi Rewards, DBS Woman’s World Card).
Petrol
| Card | Earn Rate | Remarks |
| Maybank World Mastercard Apply |
4 mpd | No cap Review |
For petrol, the best card to use really depends on which chain you frequent the most, because the goal is to stack 4 mpd with the highest discount possible.
In my case, Shell is the most convenient, which means I use the Maybank World Mastercard for an uncapped 4 mpd, with no minimum spend necessary (there’s a further 15% discount from the Corporate Fuel Card). Do note that this only applies to in-person payments made in Singapore, so payments made through apps or overseas won’t qualify.
| ❓ Why not the UOB Visa Signature? |
| The UOB Visa Signature also earns 4 mpd for petrol, but I’d prefer to conserve that cap for contactless payments instead since it’s much more flexible. |
However, I’m not dogmatic about this. I’m just as likely to use Kris+ with the DBS Woman’s World Card when at Esso, which offers an extra 2 mpd on top of the standard 4 mpd reward. Alternatively, if I see a Sinopec then I can just take advantage of the 23+% discount with any 4 mpd card at my disposal.
Public Transport
| Card | Earn Rate | Remarks |
| DBS yuu AMEX Apply |
10 mpd | Min. spend of S$800 & cap of S$823 per c. month. Must spend at 4x participating merchants Review |
| DBS yuu Visa Apply |
10 mpd | |
| UOB Preferred Visa Apply |
4 mpd | Max S$600 per c. month, must use mobile payments Review |
| UOB Visa Signature Apply |
4 mpd | Min S$1K, max S$1.2K per s. month on contactless & petrol Review |
SimplyGo is one of the easiest ways of clocking one merchant towards the DBS yuu Card’s four merchant minimum, and the fact that you earn 10 mpd doesn’t hurt either.
Alternatively, if I need to conserve my yuu cap for elsewhere, I could use the UOB Preferred Visa or UOB Visa Signature instead, since they now recognise SimplyGo bus and MRT rides as contactless spend.
Travel
| Card | Earn Rate | Remarks |
| Maybank XL Rewards Apply |
4 mpd | Min. S$500, max S$1K per c. month Review |
| HSBC Revolution Apply |
4 mpd | Max S$1K per c. month Review |
| KrisFlyer UOB Credit Card Apply |
3 mpd | SIA & Scoot. No cap Review |
| Maybank Horizon Visa Signature Apply |
2.8 mpd | Min. S$800 per c. month, capped at S$10K Review |
For air tickets, the Maybank XL Rewards and HSBC Revolution both earn 4 mpd.
However, given that both of them are capped at just S$1,000 per calendar month — and the fact that I might use them for other categories of spending — I need some uncapped options too. That comes in the form of the KrisFlyer UOB Credit Card (uncapped 3 mpd for SIA and Scoot) and Maybank Horizon Visa Signature (2.8 mpd on air tickets in general, with a S$10,000 monthly cap).
For hotels, the Maybank XL Rewards and HSBC Revolution also work, though if the transaction is in FCY I can also bring in the cards from the FCY section.
yuu Merchants
| Card | Earn Rate | Remarks |
| DBS yuu AMEX Apply |
10 mpd | Min. spend of S$800 & cap of S$823 per c. month. Must spend at 4x participating merchants Review |
| DBS yuu Visa Apply |
If you’re spending at a yuu merchant, there is absolutely no question about which card you should use: the DBS yuu AMEX or DBS yuu Visa (or both, since they each have their own bonus cap) for 10 mpd.
| Participating Merchant | Consists Of |
| 🏪 7-Eleven |
|
| 🍵 CHAGEE |
|
| ⚡Charge+ Visa only |
|
| 🛒 Cold Storage |
|
| 🍽️ FoodPanda |
|
| 🛒 Giant |
|
| 💊 Guardian |
|
| 🚕 Gojek |
|
| 📱 Singtel |
|
| 🚆 SimplyGo* |
|
| *SimplyGo is not a yuu merchant per se, but is still eligible for the bonus earn rate |
|
The only speed bump here is the minimum spend of S$800 per calendar month, but between groceries, food delivery, pharmacy items and ride-hailing, it’s doable for me— especially since I discovered the wonders of Singtel Billing, which allows you to charge app store purchases, Cast.sg apps and subscriptions, and Singtel PayLater phones and gadgets to your Singtel bill.
Since this gets asked a lot, I want to clarify that the minimum spend need not be on yuu merchants alone. However, I find it a waste to spend on non-yuu merchants because you’ll earn just 0.14 mpd, which will drag down your overall earn rate. Even if you’re slightly short of the minimum spend, buying Cold Storage or Giant vouchers would be a better way of making up the balance than non-yuu spend.
What other cards can you consider?
Chocolate Visa Card
 Chocolate Visa Card |
|||
| Apply |
It’s been a mixed year for the Chocolate Visa Card.
In September 2026, the monthly spending cap for its 1 Max Mile per S$1 earn rate was doubled to S$2,000, and the monthly bill payment cap tripled to 300 Max Miles.
But one of the biggest use cases for the Chocolate Visa Card was fee-free overseas spending, and that’s run right smack into the Trust Freedom Card, which offers better earn rates. Because of this, the use cases for Chocolate are fewer than ever before, and I only really use it to earn 300 Max Miles a month on things like insurance and utilities.
I’ve done a detailed comparison of the Chocolate Visa Card and Trust Freedom Card below, highlighting the situations where you’d choose one over the other.
GXS Credit Card
A cashback card? Here???
Well, first of all, I’ll have you know that the GXS Credit Card earns GrabCoins, not cashback, at least where Grab is concerned. And since it offers 50 GrabCoins per S$1 — equivalent to a 10% rebate — on overseas Grab spending with no minimum spend, I’ll gladly use this on my travels, and conserve my 4 mpd cards for other uses.
GrabCoins have a nominal value of 0.2 cents each, but you can get outsized value for them during the monthly Grab Flash Sales.
UOB Lady’s Card
Depending on who you ask, the UOB Lady’s Card might actually be superior to the UOB Lady’s Solitaire now, because some people find 4 mpd on up to S$1,000 in a single category more useful than 4 mpd on up to S$750 across two categories.
I’ve made the case for and against downgrading in the post below.
StanChart Beyond Card
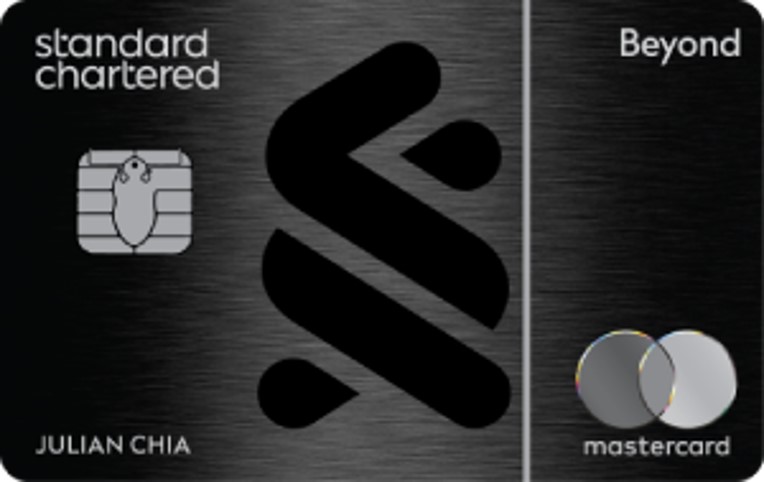
The StanChart Beyond Card has a hefty S$1,635 annual fee, and if you’ve decided to take the plunge, you’d better start using it religiously.
Not only do you have a minimum spend of S$20,000 to meet for the welcome bonus, but this card’s mechanics are structured in a way that the more you spend, the more you get rewarded.
| Regular | Priority Banking | Priority Private | |
| Welcome Offer | 100,000 miles |
||
| Local Earn | 1.5 mpd | 2 mpd | 2 mpd |
| FCY Earn | 3 mpd | 3.5 mpd | 4 mpd |
| FCY Dining | 8 mpd | ||
The local earn rates of 1.5-2 mpd are already good for a general spending card, but what’s even more impressive is the FCY earn rates of 3-4 mpd (and 8 mpd for overseas dining if you’re a Priority Private customer).
StanChart Smart Card
The StanChart Smart Card — no longer accepting new applications — earns up to 9.3 mpd on streaming, public transport, electric car charging and fast food, but there’s a big catch here. You need to spend at least:
- S$800 per statement month to earn 7.4 mpd (Tier 1)
- S$1,500 per statement month to earn 9.3 mpd (Tier 2)
I don’t know about you, but I would find it very difficult to spend that much on bonus categories alone, though I’m sure there’ll be some who could make it work (e.g. a Grab driver with an EV).
That said, you could also meet the minimum spend by spending on non-bonus categories (where the regular earn rate of 0.46 mpd, but increases to 0.93 mpd if you spend at least S$1,500). This would drag down the average earn rate, but might still make sense depending on the split of bonus vs non-bonus spend.
| Tier 1 (Min. Spend = S$800) |
|||
| Bonus Spend | Non-Bonus Spend | Total Miles | Weighted Avg. |
| S$400 7.42 mpd |
S$400 0.46 mpd |
3,152 | 3.94 mpd |
| S$500 7.42 mpd |
S$300 0.46 mpd |
3,848 | 4.81 mpd |
| S$600 7.42 mpd |
S$200 0.46 mpd |
4,544 | 5.68 mpd |
| S$700 7.42 mpd |
S$100 0.46 mpd |
5,240 | 6.55 mpd |
| Tier 2 (Min. Spend = S$1,500) |
|||
| Bonus Spend | Non-Bonus Spend | Total Miles | Weighted Avg. |
| S$500 9.28 mpd |
S$1,000 0.93 mpd |
5,570 | 3.71 mpd |
| S$600 9.28 mpd |
S$900 0.93 mpd |
6,405 | 4.27 mpd |
| S$700 9.28 mpd |
S$800 0.93 mpd |
7,240 | 4.83 mpd |
| S$800 9.28 mpd |
S$700 0.93 mpd |
8,075 | 5.38 mpd |
| S$900 9.28 mpd |
S$600 0.93 mpd |
8,910 | 5.94 mpd |
| S$1,000 9.28 mpd |
S$500 0.93 mpd |
9,745 | 6.50 mpd |
| S$1,100 9.28 mpd |
S$400 0.93 mpd |
10,580 | 7.05 mpd |
| S$1,200 9.28 mpd |
S$300 0.93 mpd |
11,415 | 7.61 mpd |
| S$1,300 9.28 mpd |
S$200 0.93 mpd |
12,250 | 8.17 mpd |
| S$1,400 9.28 mpd |
S$100 0.93 mpd |
13,085 | 8.72 mpd |
General spending cards
I make it a point to avoid general spending cards as much as possible, for the simple reason that you shouldn’t earn 1.2-1.6 mpd when you could be earning 4 mpd.
However, general spending cards can still be part of a sound miles strategy, in situations where:
- There’s a lucrative welcome offer
- You’ve exhausted the bonus caps on higher-earning specialised spending cards
- You have a big-ticket transaction that can’t be split across multiple cards
- There’s a limited-time promotion that upsizes the earn rates
- You’re using CardUp or Citi PayAll, which aren’t eligible for bonuses with specialised spending cards
In these situations, it’s all about picking the highest-earning general spending card there is.
Final reminders
Don’t forget Kris+
Whenever you’re at a restaurant, store, spa or hotel, always be sure to check whether they’re a Kris+ merchant, because that’s an easy opportunity to stack a further 0.5-9 mpd on top of your credit card miles.
 |
|||
| S$5 for new Kris+ Users | |||
| Get S$5 when you sign up with code W644363 and make your first transaction |
I’ve written a separate guide on the best cards to use with Kris+, which can be found below.
Don’t over-optimise
As much as we want to maximise 4 mpd everywhere, is it possible to overdo it?
Definitely. The way I see it, there are two additional considerations:
(1) Conversion Fees
By spreading your cards across multiple banks, you’re collecting different points currencies and will have to pay multiple conversion fees.
However, I’m not too worried about this. Conversion fees are annoying and we try to minimise them where we can, but paying them isn’t the end of the world. In the grand scheme of things, an extra S$27 here and there isn’t going to destroy the overall value proposition of the miles game.
| 💰 Points Conversion Fees by Bank |
||
| Issuer | Per Conversion | Annual Option |
 |
Free | N/A |
 |
S$30 | N/A |
 |
S$27.251 | N/A |
 |
S$27.252 | S$43.603 |
 |
Free | N/A |
 |
S$27.25 | N/A |
 |
S$25 | N/A |
 |
S$27.25 | N/A |
 |
S$27.25 | N/A |
 |
S$274 | N/A |
| 1. Waived for Citi ULTIMA Card 2. Waived for DBS Insignia Card 3. Automatic conversions in blocks of 500 DBS points (1,000 miles) each quarter. Additional ad-hoc redemptions can be done for free. Waived for DBS Insignia Card 4. Waived for UOB Reserve, UOB Visa Infinite Metal, UOB Visa Infinite and UOB Privilege Banking Card |
||
Moreover, it doesn’t necessarily mean more cards = more fees. If you own multiple cards from the same bank, you may still pay only a single conversion fee, provided the points are pooled.
For example, a UOB customer could hold a UOB PRVI Miles, UOB Preferred Visa, UOB Visa Signature and UOB Lady’s Card, all while paying only a single conversion fee.
(2) Orphan Points
Orphan points are a bigger concern than conversion fees. If you spread yourself too thin, you may end up in a situation where you’re optimising on individual transactions, but not in an overall sense.
To illustrate, suppose I drive infrequently but get a Maybank World Mastercard just so I can earn 4 mpd on petrol. I may be optimising on that particular transaction, but it counts for very little if I end up with a small chunk of TREATS points that I can’t cash out.
All things equal, non-pooling credit card points with larger minimum conversion blocks are more likely to result in orphan points.
| ✈️ Min. Conversion Blocks for KrisFlyer Miles | ||
| Currency | Points |
Miles |
| AMEX Membership Rewards Pool |
500 (Plat. Charge, Centurion) |
250 |
| 550 (All others) |
||
| BOC Points | 50K | 10K |
| Citi Miles | 10K | 10K |
| Citi ThankYou Points | 25K | 10K |
| DBS Points Pool |
5K | 10K |
| HSBC Points Pool |
35K^ (+7 beyond this) |
10K^ (+2 beyond this) |
| Maybank TREATS Pool |
25K | 10K |
| OCBC$ Pool |
25K | 10K |
| OCBC 90°N Miles Pool |
1K | 1K |
| OCBC VOYAGE Miles | 1 | 1 |
| SC 360° Rewards Points Pool* |
25K (Tier 1)* |
10K |
| 34.5K (Tier 2)* |
||
| UOB UNI$ Pool |
5K | 10K |
| *Tier 1 cards= Beyond, Journey, Priority Banking Visa Infinite, Visa Infinite, Tier 2 cards= All others. No pooling of Tier 1 and Tier 2 points ^Refers to the KrisFlyer conversion rate; other programmes start from 25K points = 10K miles |
||
tl;dr: Optimisation is good, but you need to look at both the micro and macro picture. If you don’t spend a significant amount on a particular category, then consider using a blacklist card like the Citi Rewards or UOB Preferred Visa, or even a general spending card instead.
Quality vs quantity of points
Not all credit card points are made equal. They differ in terms of:
In other words, two cards could offer 4 mpd, but one card’s 4 mpd might be more valuable than the other’s. I personally consider AMEX Membership Rewards points, Citi Miles/ThankYou points and HSBC points to be the three most valuable rewards currencies in Singapore.
| Programme |  AMEX |  BOC |  Citi |  DBS |  HeyMax |  HSBC |  Maybank |  OCBC |  SCB |  Trust |  UOB |
|---|---|---|---|---|---|---|---|---|---|---|---|
 Star Alliance | |||||||||||
 Singapore AirlinesKrisFlyer | Yes, instant transfer | Yes | Yes | Yes | No | Yes, instant transfer, haircut rate | Yes | Yes | Yes | Yes, instant transfer | Yes |
 Air CanadaAeroplan | No | No | No | No | No | Yes, instant transfer, haircut rate | No | No | No | No | No |
 Air IndiaMaharaja Club | No | No | No | No | Yes | No | No | No | No | No | No |
 Ethiopian AirlinesShebaMiles | No | No | No | No | Yes, instant transfer | No | No | No | No | No | No |
 EVA AirInfinity MileageLands | Yes | No | Yes | No | Yes, instant transfer | Yes, instant transfer | No | No | No | No | No |
 Thai AirwaysRoyal Orchid Plus | Yes | No | Yes | No | No | Yes, instant transfer, haircut rate | No | No | No | No | No |
 Turkish AirlinesMiles&Smiles | No | No | Yes | No | Yes, instant transfer | Yes, instant transfer, haircut rate | No | No | No | No | No |
 United AirlinesMileagePlus | No | No | No | No | No | Yes, instant transfer, haircut rate | No | Yes, instant transfer, haircut rate | No | No | No |
 oneworld | |||||||||||
 British AirwaysBritish Airways Club | Yes | No | Yes | No | No | Yes, instant transfer | No | Yes, instant transfer, haircut rate | No | No | No |
 Cathay PacificAsia Miles | Yes | No | Yes | Yes | Yes | Yes, instant transfer | Yes | Yes, instant transfer, haircut rate | Yes | No | Yes |
 Japan AirlinesJAL Mileage Bank | No | No | No | No | Yes, instant transfer | Yes, haircut rate | No | No | No | No | No |
 Malaysia AirlinesEnrich | Yes | No | No | No | Yes, instant transfer | No | Yes | No | No | No | No |
 QantasQantas Frequent Flyer | Yes, instant transfer | No | Yes | No | No | Yes, instant transfer | No | No | No | No | No |
 Qatar AirwaysQatar Privilege Club | No | No | Yes | No | Yes, instant transfer | Yes, instant transfer, haircut rate | No | No | No | No | No |
 SkyTeam | |||||||||||
 Air France-KLMFlying Blue | No | No | Yes | No | Yes, instant transfer | Yes, instant transfer | No | Yes, instant transfer | No | No | No |
 Garuda IndonesiaGarudaMiles | No | No | No | No | Yes, instant transfer | No | No | No | No | No | No |
 SASEuroBonus | No | No | No | No | Yes, instant transfer | No | No | No | No | No | No |
 Vietnam AirlinesLotusmiles | No | No | No | No | Yes, instant transfer | Yes, instant transfer | No | No | No | No | No |
 Xiamen AirlinesEgret Miles | No | No | No | No | Yes, instant transfer | No | No | No | No | No | No |
| Other airlines | |||||||||||
 AirArabiaAir Arabia Rewards | No | No | No | No | Yes, instant transfer | No | No | No | No | No | No |
 AirAsiaAirAsia Rewards | No | No | No | Yes | Yes, instant transfer | Yes, instant transfer | Yes | No | No | No | Yes |
 Air AstanaNomad Club | No | No | No | No | Yes, instant transfer | No | No | No | No | No | No |
 EmiratesSkywards | Yes, instant transfer, haircut rate | No | No | No | No | No | No | No | No | No | No |
 Etihad AirwaysEtihad Guest | No | No | Yes | No | No | Yes, instant transfer | No | Yes, instant transfer, haircut rate | No | No | No |
 Hainan AirlinesFortune Wings | No | No | No | No | No | Yes, haircut rate | No | No | No | No | No |
 Philippine AirlinesMabuhay Miles | No | No | No | No | Yes | No | No | No | No | No | No |
 VietJet AirSkyJoy | No | No | No | No | Yes | No | No | No | No | No | No |
| Hotels | |||||||||||
 AccorAccor Live Limitless | Yes | No | No | No | Yes, instant transfer | Yes, instant transfer | No | Yes, instant transfer | No | No | No |
 Hilton Honors | Yes | No | No | No | No | No | No | No | No | No | No |
 IHGIHG One Rewards | No | No | Yes | No | Yes, instant transfer | Yes, instant transfer | No | Yes, instant transfer | No | No | No |
 MarriottMarriott Bonvoy | Yes | No | No | No | No | Yes, instant transfer | No | Yes, instant transfer | No | No | No |
 RadissonRadisson Rewards | No | No | No | No | Yes, instant transfer | No | No | No | No | No | No |
 Shangri-LaShangri-La Circle | No | No | No | No | Yes, instant transfer | No | No | No | No | No | No |
 WyndhamWyndham Rewards | No | No | No | No | Yes, instant transfer | Yes, instant transfer | No | No | No | No | No |
| Points currencies | |||||||||||
| HeyMaxHeyMax | No | No | No | Yes, instant transfer | No | No | No | No | No | Yes, instant transfer | No |
Because of this, I’d be more inclined to max out the online bonus cap on my Citi Rewards Card first, before switching over to my DBS Woman’s World Card.
Conclusion
The biggest shake-up to my card strategy has really come from the Trust Freedom Card, which makes me reconsider any overseas spending card that earns less than 4 mpd.
Elsewhere, the DBS yuu Card got a huge upgrade now that yuu Points can be converted into Max Miles, the Chocolate Visa Card has been relegated to bill payment duty, and CardUp has priced itself out of contention unless you’re paying through PayNow. But the core of my strategy hasn’t changed much, nor my advice for those just starting out.
Remember, for most people, a simple four-card combo of the Citi Rewards, DBS Woman’s World Card, UOB Preferred Visa and UOB Visa Signature will be enough to earn 4 mpd on most transactions.
The other cards come in when you:
- have specific use cases (e.g. Maybank World Mastercard for overseas education spend)
- have already burst the monthly bonus caps on those four cards
- want to take advantage of “beyond 4 mpd” opportunities (e.g. UOB Lady’s Card + Lady’s Savings Account, OCBC Rewards for Shopee & Lazada, DBS yuu for yuu merchants)
If everything remains as-is, then this should be the last update for 2026. See you in 2027…whatever that looks like!

excellent comprehensive article
2026 likely to be the same.
citi rewards (ms and visa) – online, transport, and shopping
citi pm – agoda
ocbc rewards – stop using for now as it will be come orphan miles.
uob ppv and vs – general spending on contactless and fcy but need to be care on vs.
uob krisflyer – kris+, sq, scoot and krishop
uob ladys solitaire dining and travel.
amaze + citi rewards ms if exceed $50 for FCY – jb shopping or use ppv or cash.
citi prestige if I max all above.
Is heymax considered online purchase too, that it can be paired with wwmc?
Given that you can earn 8mpd on HSBC Revolution for all of the OCBC Rewards’ 6mpd & 4mpd merchants/categories, is there really any compelling reason to keep the OCBC Rewards?
additional bonus cap?
My current stack for 2026:
Citi Rewards (Online/Apps ex. Travel/Mobile Wallet)
HSBC Revolution (Gym, Travel, Grab, Shopping, Atome, Heymax)
OCBC Voyage (CardUp, Lounge Access, Airport Limo)
UOB Lady’s Solitaire (Beauty & Wellness, Dining)
UOB PV (SimplyGo, Groceries, Misc. Mobile Contactless/Online)
UOB PRVI (Payment Facility, Misc. Spend)
UOB seems to be getting harder to get annual fees waivers these days. Had to cancel 2 cards including the preferred visa, though that could be because I rarely spend to the max cap of 600/month…
Great article!
I needed some help figuring out which card to use for mortgage payments through iPayMy now that Cardup is increasing their feeds. Any recos on Mastercard? (I can’t use Citi ones in this scenario).
Can i use UOB Preferred Visa for Atome payments to earn 4mpd under the $600 Online category?
Hi Aaron,
In July 2026, I have encountered that HealthHub and NHG Health app are already coded as Government Services when I use DBS Woman’s World Card. You may want to update this article.
thanks – will drop an update on this!